
By Elizabeth Frost, China Analyst; Danny Hartono, Data Scientist; with contributions from Lauri Myllyvirta, Lead Analyst
Coal and gas generation fell for the third consecutive month, as increased solar, wind, and nuclear generation met all additional electricity demand. Despite declining fossil fuel imports and domestic coal output, thermal power capacity additions continued to accelerate. Strong electric vehicle exports continued to drive NEV production growth, offsetting weakness in the domestic auto market.
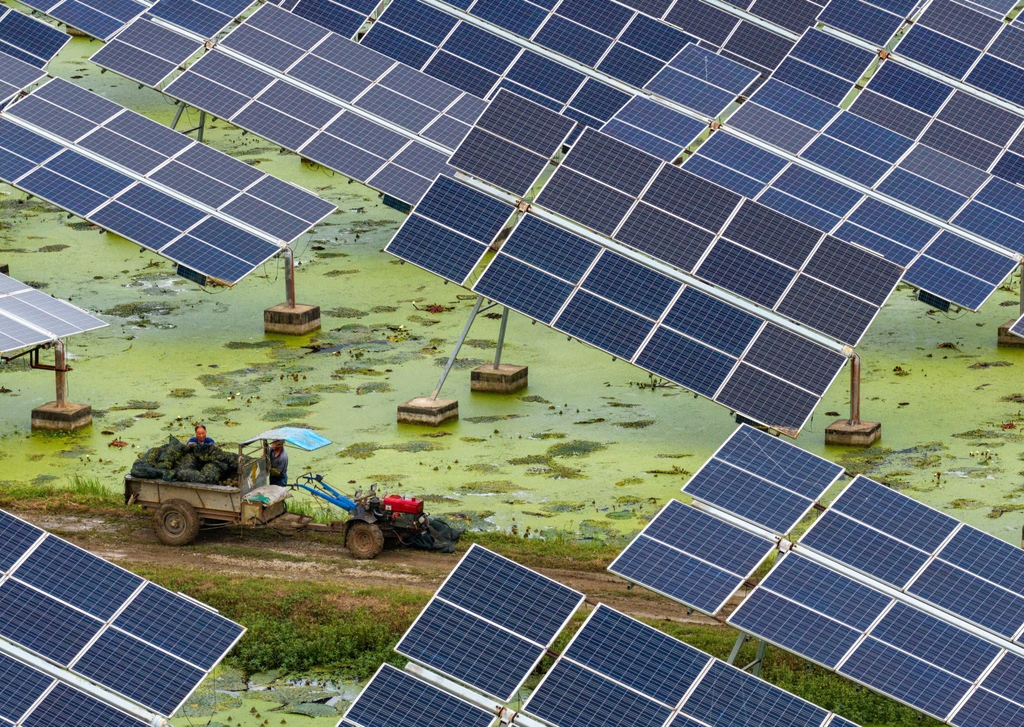
Villagers harvest water chestnuts under photovoltaic panels at the Baimahu Photovoltaic Base in Huai’an City, Jiangsu Province, China on September 27, 2026. China installed 97.2 gigawatts (GW) of solar power capacity in the first eight months of 2026. Photo: Cynthia Lee/Alamy
Key findings
- Coal and gas power generation fell 1.4% year-on-year in September, marking the third consecutive month of declining fossil generation in China. Despite a sharp fall in hydropower generation, growth in solar, wind, and nuclear generation more than covered all additional electricity demand.
- China’s fossil fuel imports and domestic coal output fell year-on-year in September, mirroring weaker consumption. Solar and wind continued to displace coal and gas in power generation, while electric vehicles and rail travel displaced oil in transport.
- Thermal power capacity additions continued to accelerate, reaching a record 58.7 GW in the first eight months of 2026. Solar and wind installations rose year-on-year in August, partly reflecting a low base in 2025.
- China’s new energy vehicle (NEV) exports reached 4 million units in the first nine months of 2026, up 130% year-on-year. Surging exports supported continued NEV production growth despite declining domestic vehicle sales.
- Carbon-intensive industries continued to stagnate, with daily crude steel production and cement output falling to multi-year lows.
Coal generation fell for the third consecutive month, as wind, solar, and nuclear generation covered all additional power demand
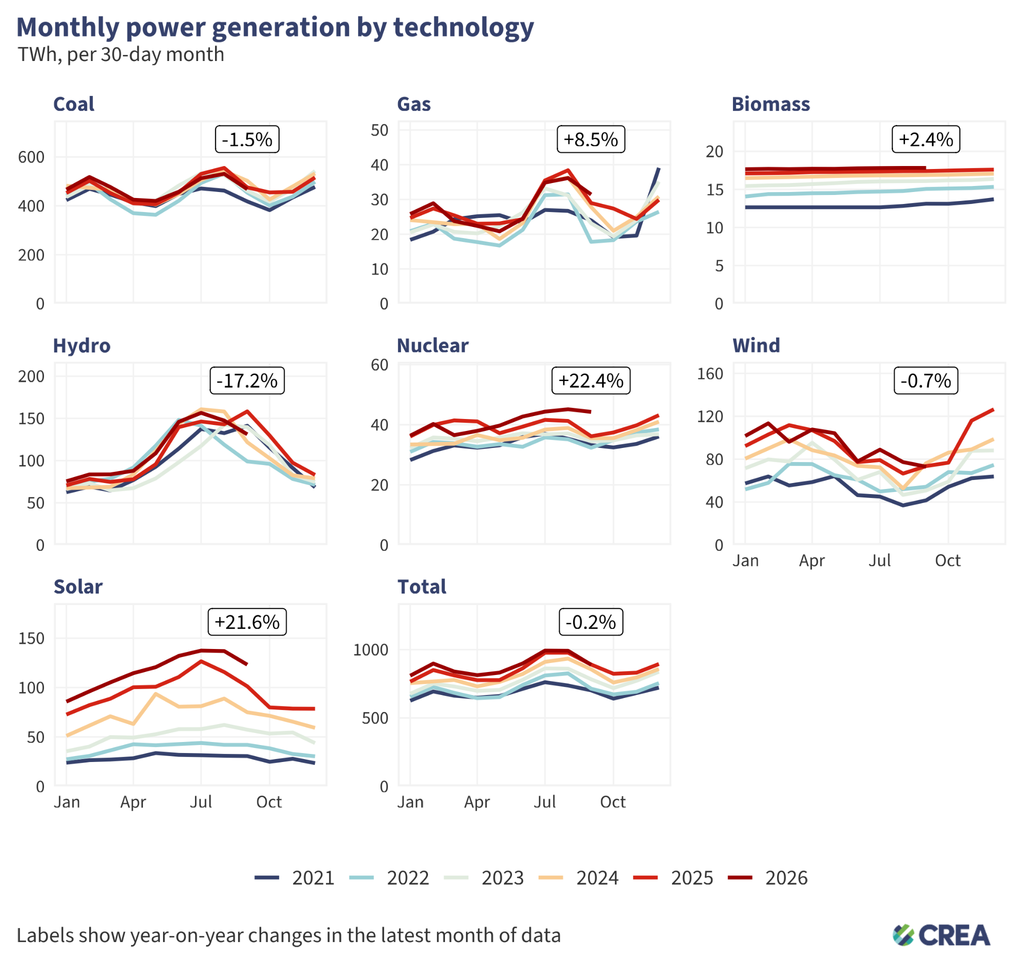
- Power generation by large-scale power producers fell 1.2% year-on-year in September, while total power generation is estimated to have have increased by 1.2%.
- Coal power generation fell 1.5% year-on-year, marking three consecutive months of decline. This followed China’s coal power generation falling for the first time in a decade in 2025.
- Gas power generation rose 8.5% year-on-year in September. However, because gas plays a minor role in China’s power mix, this increase had a limited impact on overall electricity generation: power generation from coal and gas fell 1.4% compared to the same period a year earlier.
- Solar generation rose 21.6% year-on-year.
- Wind generation rose 16.6% year-on-year, signalling wind utilisation is recovering after poor wind conditions and heavy curtailment in the first half of the year.
- Hydropower generation fell 17.2% year-on-year, predominantly due to a base effect from a 32% jump in September 2025.
- Nuclear power generation grew 22.4%, reaching a multi-year high. Nuclear power still plays a minor role in China’s power mix, so this increase had a limited impact on overall electricity generation.
*Thermal, nuclear, and hydropower generation are based on National Bureau of Statistics (NBS) data. Solar generation is estimated from installed capacity and projected utilisation rates, adjusted for weather and average curtailment over the preceding three months. Wind generation estimates are calculated using a wind projection model utilising NASA wind speed data. Figures for the most recent month are preliminary model estimates and may be revised once official generation and capacity data are released. Coal and gas generation are estimated by splitting total thermal generation using last year’s same-month fuel mix, adjusted by the year-on-year change in the fuel mix over the preceding three months.
Fossil fuel imports continued to fall in September
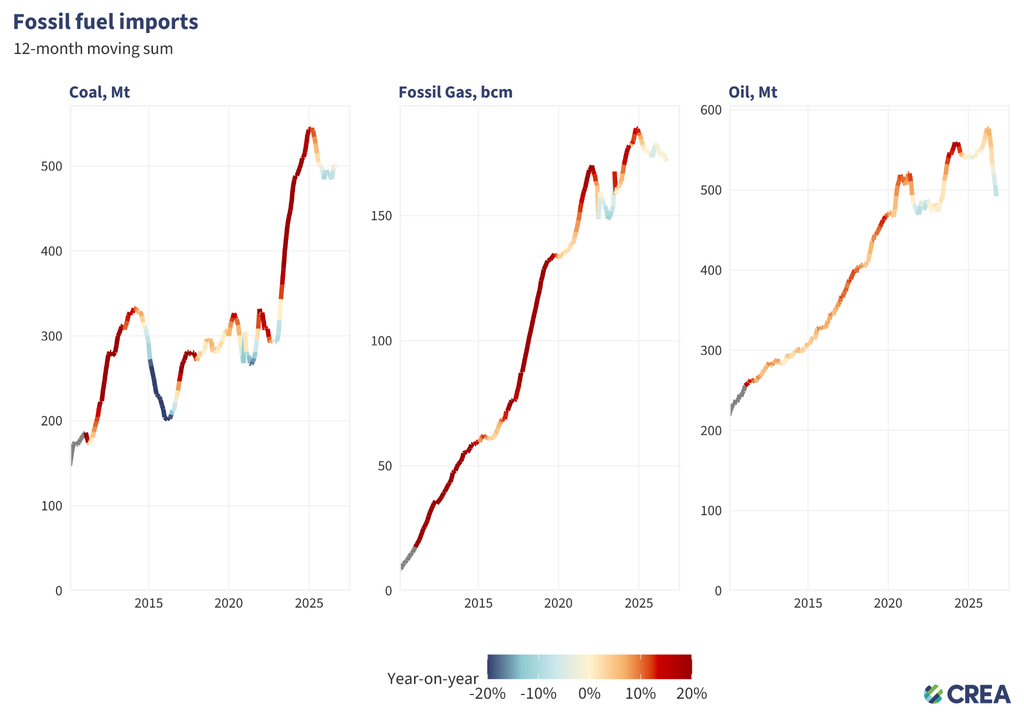
- China’s coal imports fell 5.7% year-on-year in September 2026 for the second consecutive month.
- China’s crude oil imports fell 21.5% from a year earlier, reflecting the continued impact of disruptions to shipments through the Strait of Hormuz. For the first nine months of the year, crude oil import volumes fell 15.3% year-on-year.
- Natural gas imports fell by 1.7% year-on-year. Cumulative imports so far this year were 3.9% lower than during the same period in 2025.
Domestic coal output continued to contract in September
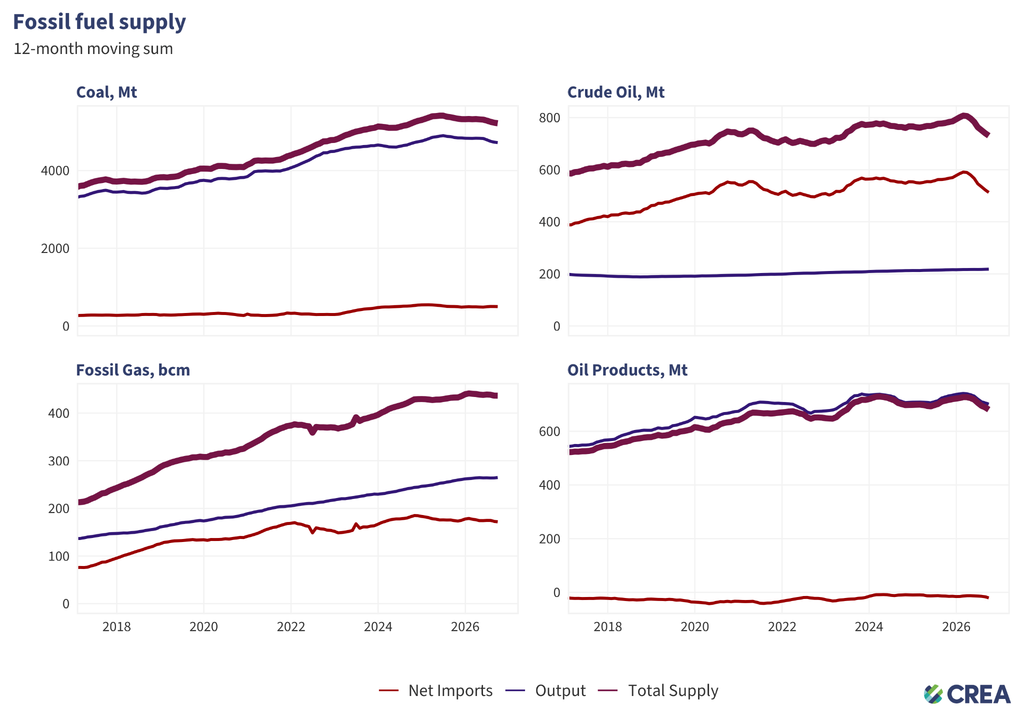
- Coal output fell 6.8% year-on-year in September 2026, bringing production in the first nine months of the year down 3.5% from the same period in 2025.
- Natural gas output fell 1% year on year in September, while total output across the first nine months of 2026 rose 0.9%.
- Crude oil production increased by 2.2%. Output in the first nine months increased by 1%.
- Crude throughput fell 8.4% year-on-year in September.
Carbon-intensive industrial output continued to stagnate; crude steel output remained flat
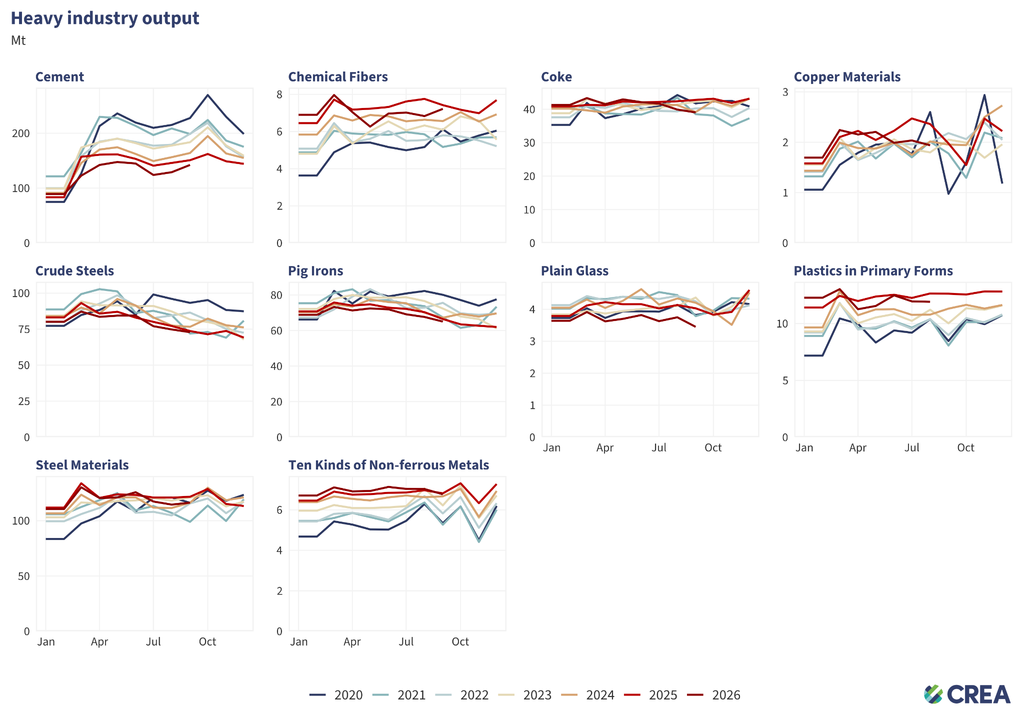
- Crude steel output rose 0.1% year-on-year in September, with cumulative output down 2.9% so far this year. Steel product output fell 3.8% year-on-year. Pig iron production remained at a multi-year low.
- Cement output fell 5.3% year-on-year in August, the lowest level for the same period since 2020. Output in the first nine months of 2026 was down 8.6% year-on-year, reflecting the decline in China’s real estate sector.
- Chemical fibre output rose 0.4% year-on-year, ending a five-month decline that began in April. Non-ferrous metal output rose 0.1% year-on-year.
- Sulfuric acid output fell by 12.4% due to the continued impacts of shipping disruptions in the Strait of Hormuz, affecting supplies of this key input for phosphate fertiliser production.
The steel and cement industries are the largest CO2 emitters in China, when emissions from their electricity use are included. They are also bellwethers of real estate, infrastructure, and other fixed-asset investments that play an outsized role in China’s emissions and economy. Sulfuric acid and chemical fibre output indicate wider trends in China’s emissions-intensive chemicals sector.
Average daily crude steel output hit a multi-year low in early October
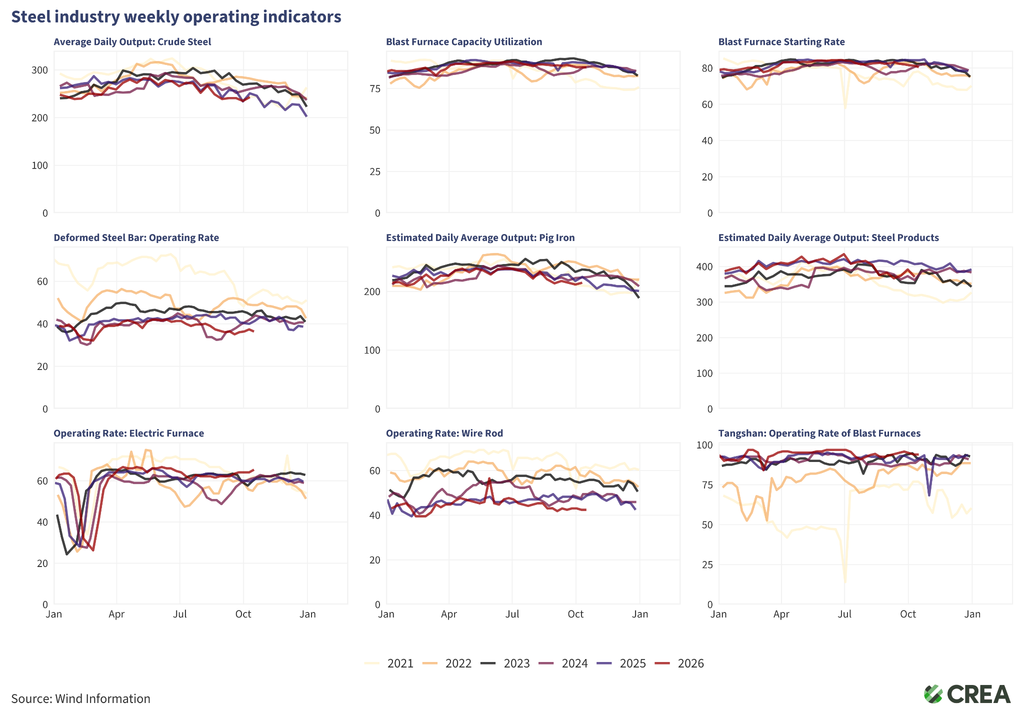
- Blast furnaces for steel production remained active in the second week of October, with a starting rate of 81.4% and utilisation reaching 87.8%. Electric furnace operating rates stayed at 64.1%, slightly above the same period last year.
- Daily crude steel output fell to the lowest level for the same period since 2021, while daily pig iron and steel products output dropped 4.4% and 8.8% year-on-year, respectively.
- The operating rate of blast furnaces in Tangshan, China’s ‘steel capital’ and a major source of regional air pollution, reached 93.9% in early October, the highest level for this period in several years.
Hebei Province industrial output is a bellwether of national priorities: when air quality and emissions are priorities, it is the most tightly regulated area because of its impact on Beijing’s pollution levels. Read our September 2026 Air Quality Trends Snapshot here.
Thermal power additions reach a record high for the first eight months of the year
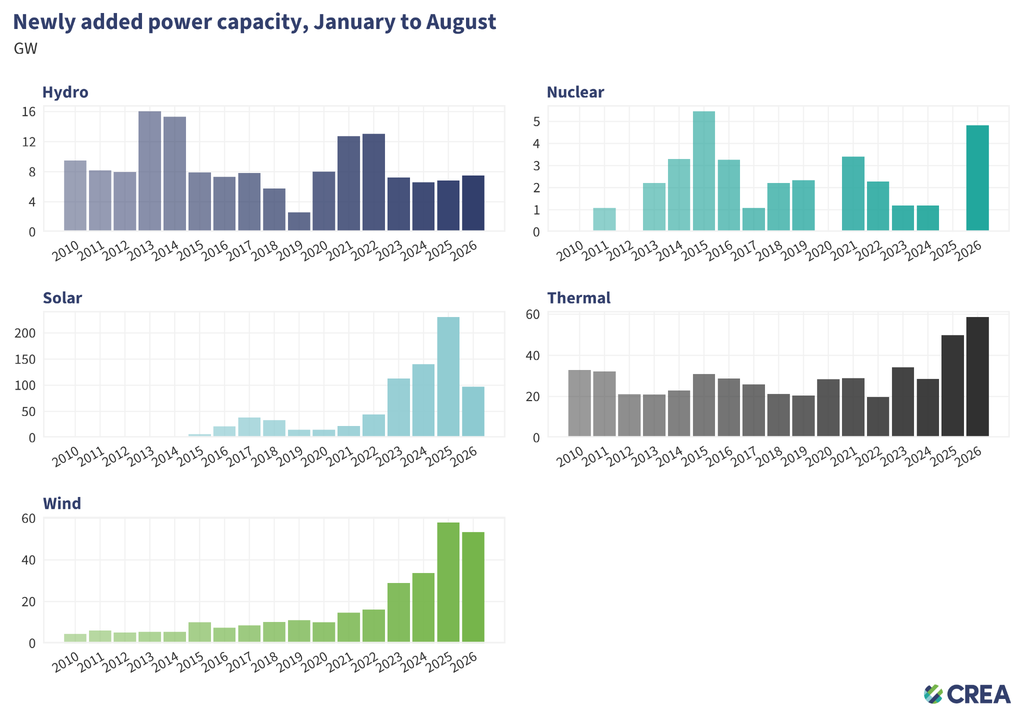
In the first eight months of 2026, China added:
- 97.2 gigawatts (GW) of solar power capacity, down 58% from a very high baseline in 2025 and the lowest level of additions in the first eight months of a year since 2022;
- 53.3 GW of wind power capacity, down 8% from a similarly high baseline last year, but still higher than the level of additions in any year prior to 2025.
- 58.7 GW of thermal power capacity, up 18% from last year, the highest level in the same period of the last 15 years. 2026 is expected to be one of the highest years on record for new coal power capacity coming online.
- 7.5 GW of hydro power capacity, up 10% from last year;
- 4.8 GW of nuclear power capacity, up from 0 GW in the same period last year.
In August 2026 alone, China added:
- 11.1 GW of solar power capacity, up 51% from August last year;
- 6.2 GW of wind power capacity, up 48% from last year. Increased solar and wind capacity additions are due to a base effect from a slump in August 2025, a result of the installation rush ahead of new price reforms in early 2025;
- 8.4 GW of thermal power capacity, up 7% from August last year;
- 0.7 GW of hydro power capacity, down 25% from August last year;
- 1.2 GW of nuclear power capacity, up from 0 GW installed in August 2025.
Large-scale clean energy bases continued to lead in wind and solar installations
- Solar power installations this year are led by Jiangsu, Henan, Yunnan, and Xinjiang. Yunnan and Xinjiang’s strong showing is notable, as both are set to host new large-scale clean energy bases under a 15th Five-Year Plan (FYP) initiative.
- Wind development was led by Xinjiang, Inner Mongolia, and Shandong. Inner Mongolia is also part of the 15th FYP large-scale clean energy bases initiative.
- Thermal (mainly coal) power additions accelerated in Anhui, Hubei, Guangdong, and Hebei.
Read more: China Coal Power Biannual Review – H1 2026
Solar production decline slowed, as battery production remained robust
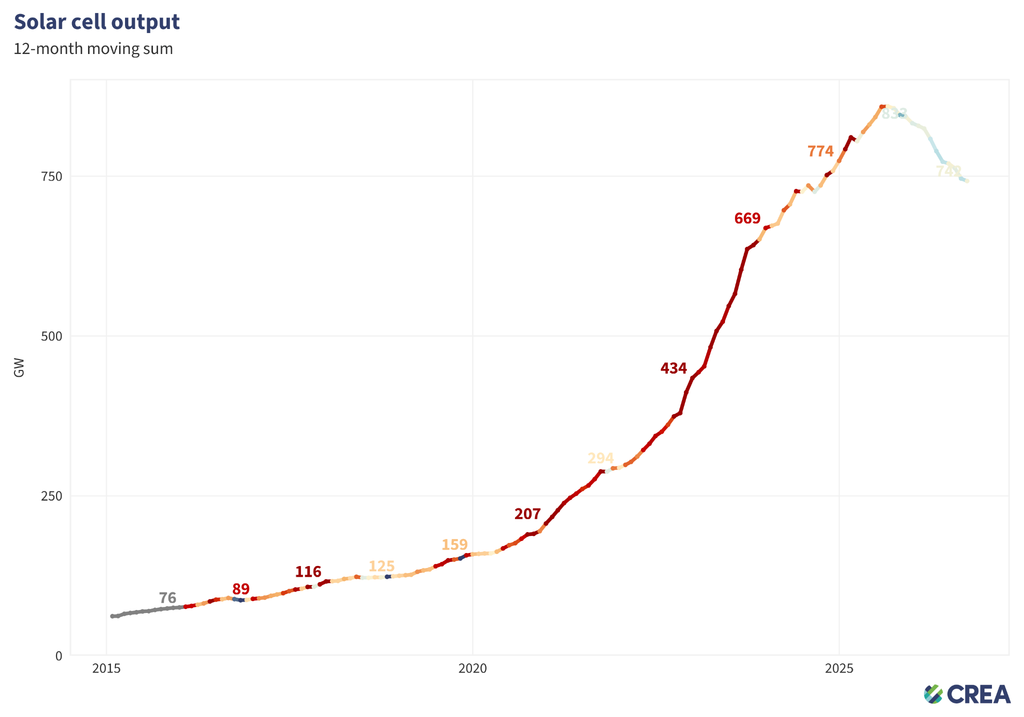
- Solar cell production fell again in September, down 5.1% year-on-year, but the contraction slowed compared with previous months. In the first nine months of the year, 579 GW of cells were produced; this puts 2026 output on track to comfortably exceed the 660 GW of solar capacity installed globally in 2025, signalling robust demand for solar panels from overseas and domestic markets.
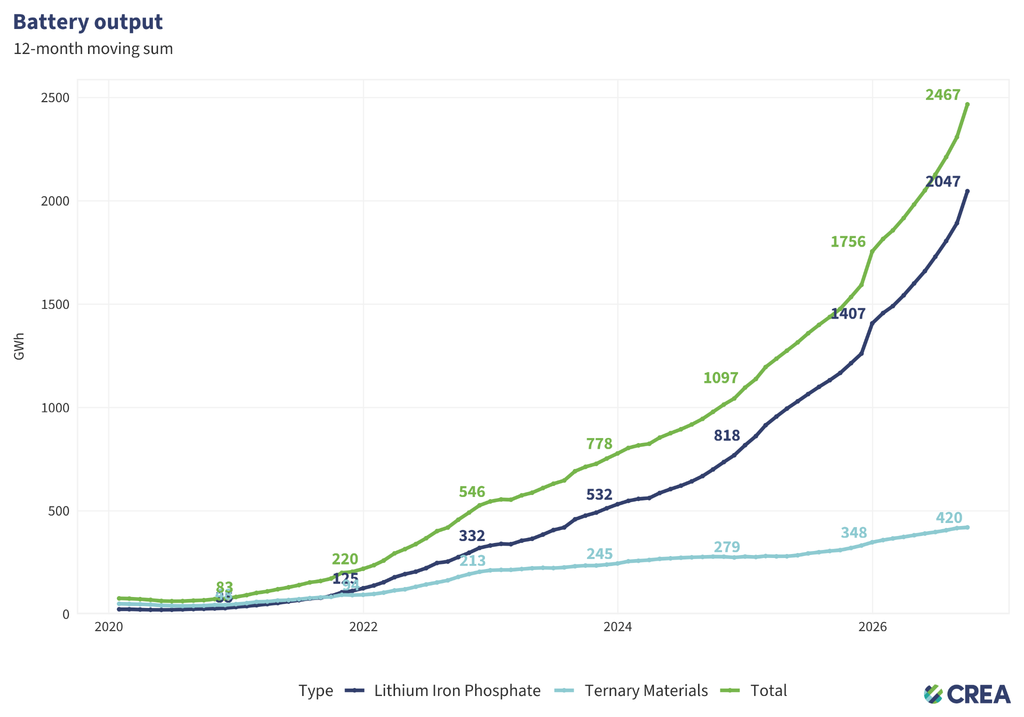
- Battery production reached 237.8 GWh in September, up 57.3% from a year earlier, driven by strong demand from energy storage and export markets.
NEV exports surged, as domestic sales continued to contract
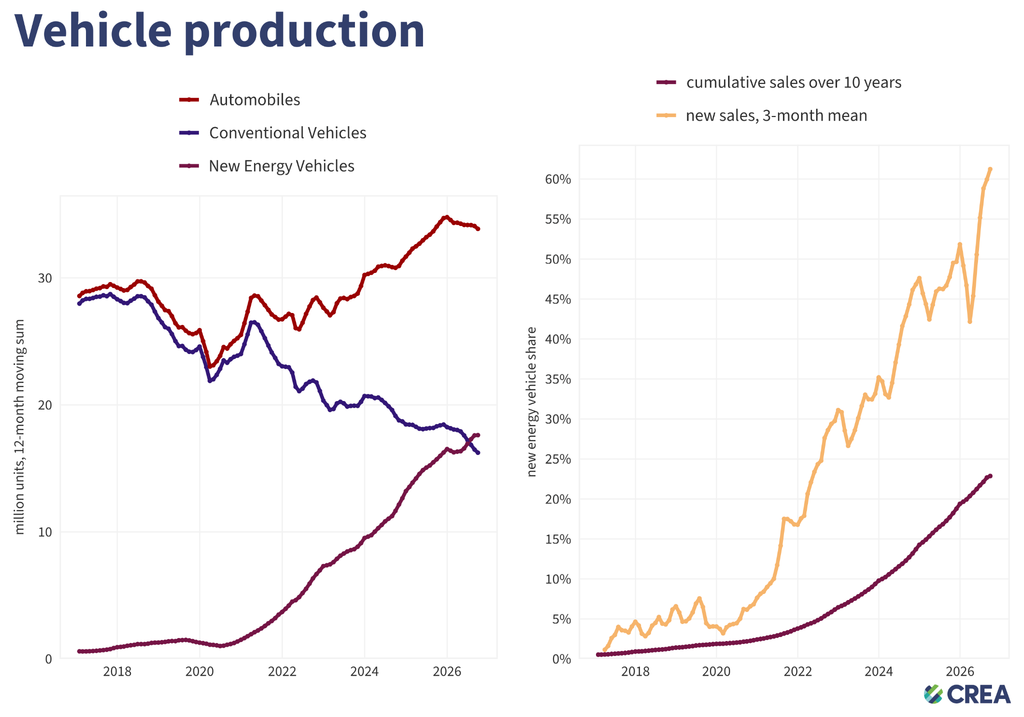
- New Energy Vehicle (NEV) production continued to expand in September, rising 16.9% year-on-year. Production in the first nine months of 2026 was up 12%. Overall vehicle production declined 5.7% in September, bringing the share of NEVs to 61% of all vehicles produced.
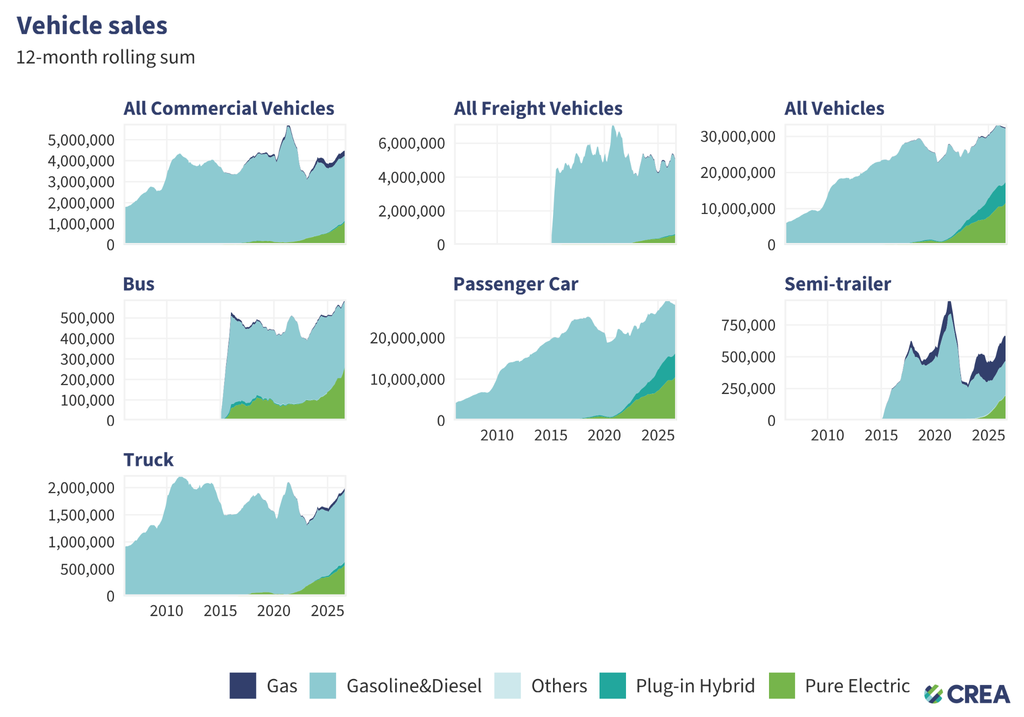
- NEV sales increased 13.6% year-on-year in September, while domestic NEV sales fell 9.4%. NEVs accounted for 65.8% of total domestic vehicle sales. In the first nine months of 2026, domestic NEV sales declined 10.6% year-on-year, largely due to the broader decline in domestic vehicle sales.
- NEV exports surged 160% year-on-year in September 2026. In the first nine months of the year, NEV exports reached 4 million units, up 130% year-on-year.
Relevant analysis by CREA:
Beyond the headline targets: What China’s 15th Five-Year Plans mean for its green transition
Five years on: China seeds overseas renewables growth but coal ban gaps persist
Analysis: China’s CO2 emissions fall in Q2 2026 due to plummeting oil use
Built for backup, contracted to run: China’s coal support system risks crowding out clean power | China Coal Power Biannual Review H1 2026
China’s new energy plan leaves emissions loose
China’s CO2 climbs 2% in early 2026 due to ‘wasted’ wind and solar
What drove China’s historic drop in power-sector emissions?
China’s new carbon metric leaves Germany-sized gap in its emissions
Reclaiming credibility in China’s steel industry: Climate ambition, financial resilience, and market trust
China’s 15th Five-Year Plan — Implications for climate and energy transition