
Indicators point to a broad-based decline in China’s emissions in August, with fossil fuel use and industrial output weakening across the power, steel, cement and refining sectors. At the same time, clean-tech manufacturing and NEV production remained strong, while thermal power capacity additions continued to accelerate.
By Qi Qin, Elizabeth Frost, China Analysts; Miao Chien, Hubert Thieriot, Data Scientists; with contributions from Lauri Myllyvirta, Lead Analyst
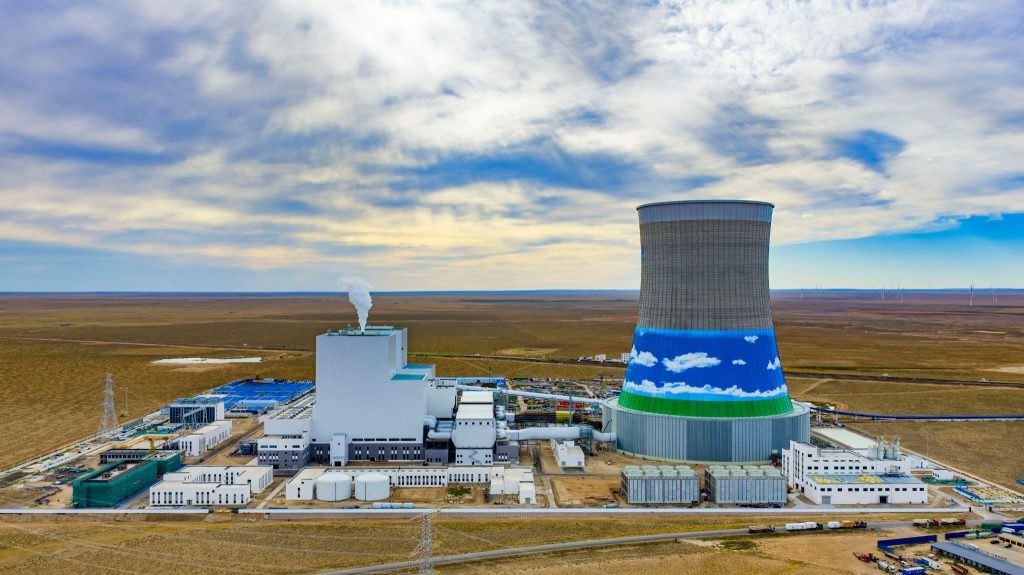
Construction of a coal power project in Xilingol League, Inner Mongolia on 25 August 2026. 2026 is expected to be one of the highest years on record for coal power additions. Photo: Cynthia Lee/Alamy
Key findings
- Indicators point to a broad-based decline in China’s emissions in August, with both the power and industrial sectors weakening. Thermal power generation fell 4% year-on-year as solar and wind covered all growth in electricity demand, while hydropower and nuclear generation also increased. Cement production fell by 12%, crude steel output by 4%, and refinery throughput by 7%.
- Fossil fuel supply remained subdued in August, with coal production and imports both falling year-on-year and oil and gas imports remaining well below 2025 levels. Refinery throughput recovered from July’s slump but was still down 6.9% year-on-year.
- Thermal power additions accelerated sharply in 2026, reaching 50.3 GW in the first seven months, up 20% year-on-year and the highest level for the period in 15 years. Additions were particularly strong in Anhui, Guangdong, Hebei, and Sichuan. Nationally, solar and wind installations slowed from last year’s exceptionally high levels.
- Clean-tech manufacturing remained strong: battery production surged 70% year-on-year, while solar cell output in the first eight months of the year remained on track to exceed the 2025 global installation level, despite a contraction in August.
- New energy vehicles (NEVs) production continued to expand despite a weaker domestic auto market, with output up 21.9% year-on-year in August and NEVs accounting for 61% of all vehicles produced. Export growth remained exceptionally strong, more than doubling both in August and over the first eight months of 2026.
Coal generation fell for the second consecutive month, as renewable generation covered all electricity demand growth
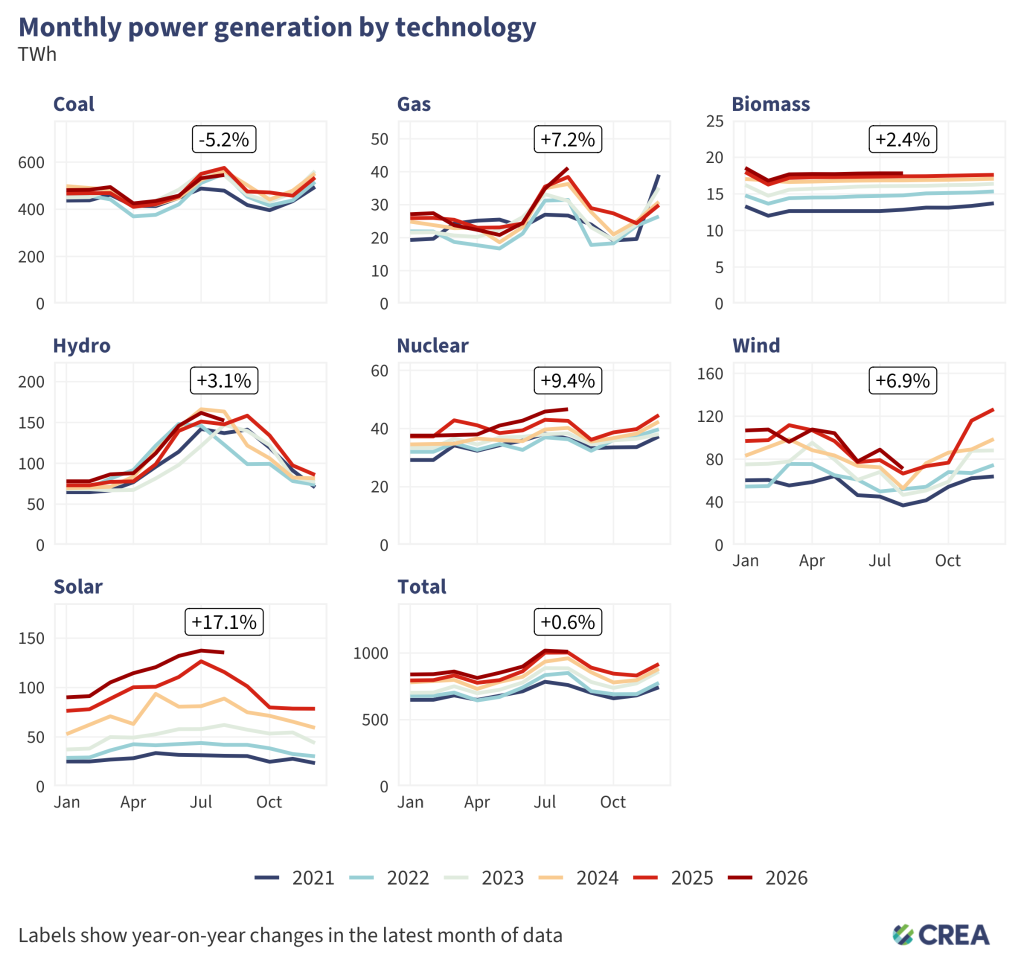
- Power generation by large-scale power producers fell 0.8% year-on-year in August, while total power generation is estimated to have increased by 0.6%.
- Coal power generation fell 5.2% year-on-year, marking two consecutive months of decline. This followed China’s coal power generation falling in 2025 for the first time in a decade.
- Gas power generation rose 7.2% year-on-year, the first increase since shipping disruptions in the Strait of Hormuz began affecting natural gas supplies. However, as gas plays a minor role in China’s power mix, this increase had a limited impact on overall electricity generation.
- Solar generation rose by 17.1% year-on-year.
- Wind generation rose 6.9% year-on-year, a rebound from the slump in earlier months caused by poor wind conditions. Increased solar and wind generation covered all electricity demand growth in August.
- Hydropower and nuclear power generation grew 3.1% and 9.4%, respectively.
*Thermal, nuclear, and hydropower generation are based on National Bureau of Statistics (NBS) data. Solar generation is estimated from installed capacity and projected utilisation rates, adjusted for weather and average curtailment over the preceding three months. Starting this month, wind generation estimates are now calculated using a new wind projection model utilising NASA wind speed data. Figures for the most recent month are preliminary model estimates and may be revised once official generation and capacity data are released. Coal and gas generation are estimated by splitting total thermal generation using last year’s same-month fuel mix, adjusted by the year-on-year change in the fuel mix over the preceding three months.
Fossil fuel imports fall in August
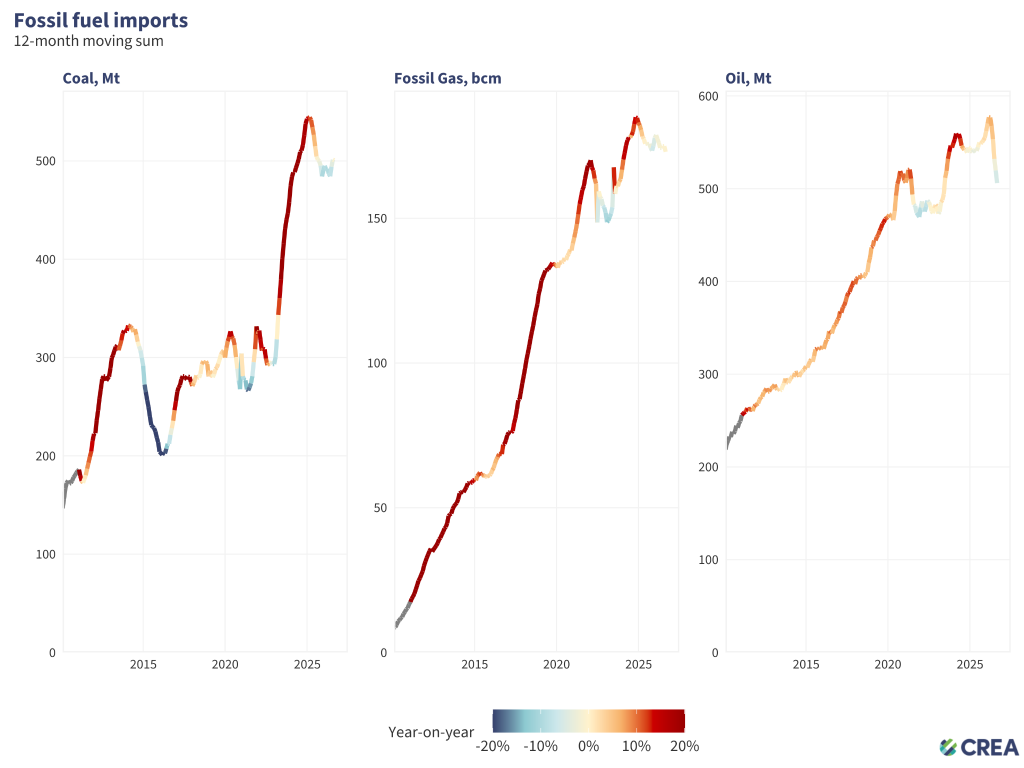
- China’s coal imports fell 1.5% year-on-year in August 2026, reversing the double-digit growth recorded in both June and July.
- China’s crude oil imports rose to a four-month high in August 2026, but remained 23% below the level a year earlier, reflecting the continued impact of disruptions to shipments through the Strait of Hormuz. For the first eight months of the year, crude oil import volumes fell 14.6% year-on-year.
- Natural gas imports fell by 13% year-on-year. Cumulative imports so far this year were 4.4% lower than during the same period in 2025.
Coal output continues to fall, as crude throughput rebounds from July lows
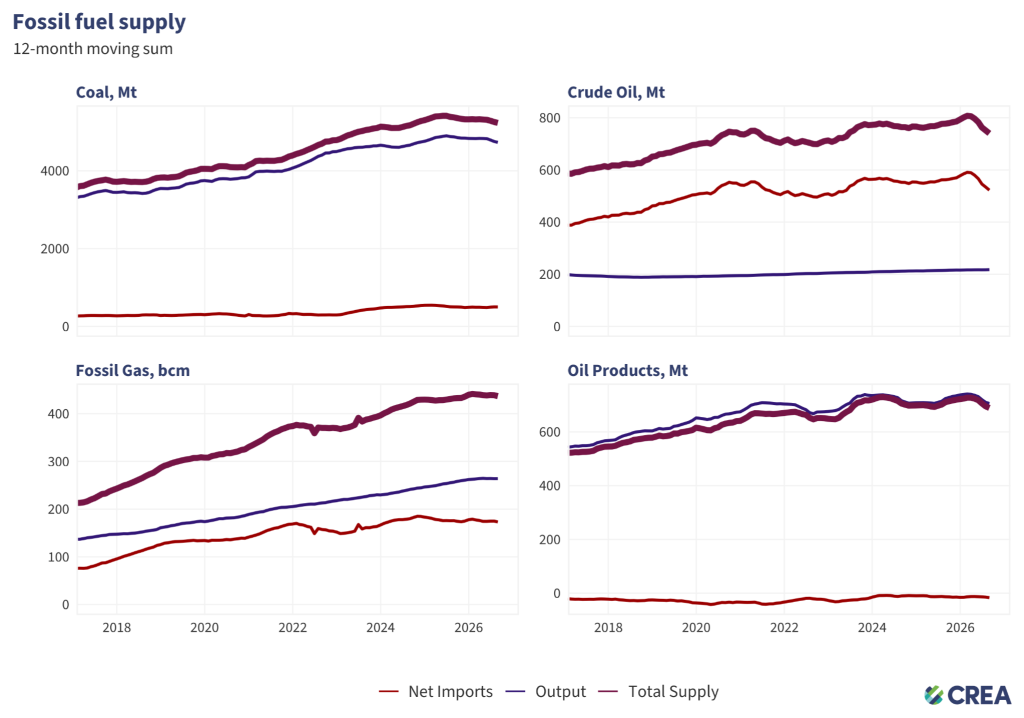
- Coal output fell 7.7% year-on-year in August 2026, bringing production in the first eight months of the year down 3.3% from the same period in 2025. Combined domestic production and imports fell by around 2.7% year-on-year over the same period.
- Domestic natural gas output increased 0.8% year-on-year in August, with total output across the first eight months of 2026 up 1.1%.
- Crude oil production increased by 0.8%. Output in the first eight months increased by 0.9%.
- Crude throughput fell 6.9% year-on-year in August, with the decline narrowing by 8.9 percentage points from July. Daily average throughput rebounded to its March level.
Carbon-intensive industrial output continues to contract, with cement output falling by more than 10%
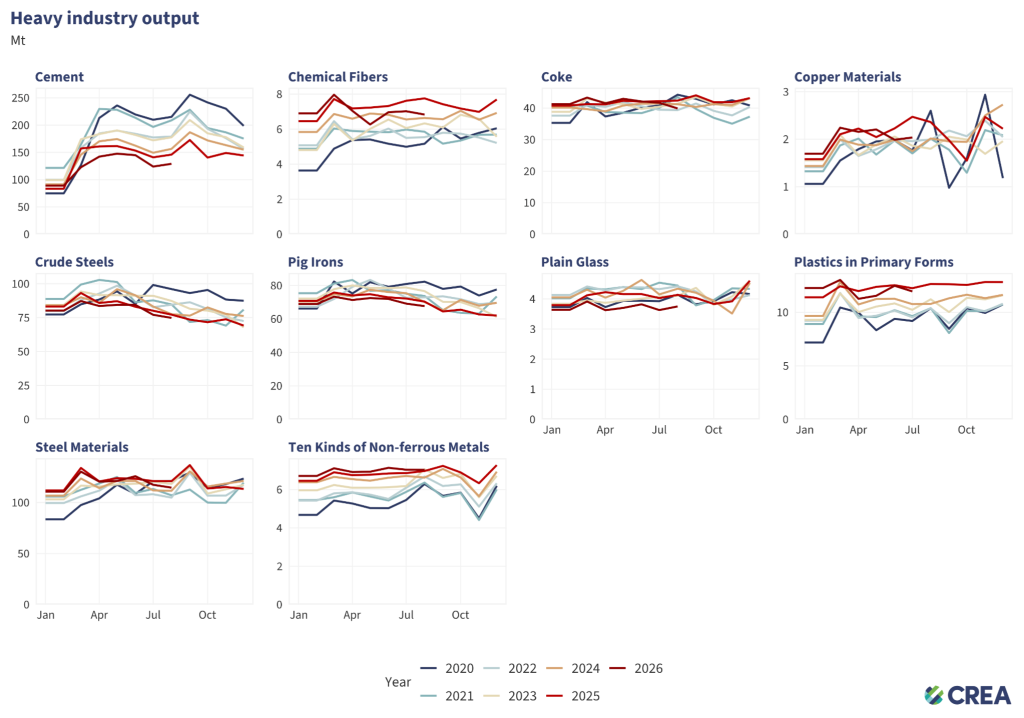
- Crude steel output fell 3.7% year-on-year in August, declining by 3.1% over the year thus far. Output of steel products fell by 5.5% compared to a year earlier. Pig iron production also declined, falling 3.5% year-on-year.
- Cement output continued to contract, falling 11.7% year-on-year in August, staying at its lowest level for the same period since 2020. Output in the first eight months of 2026 is down 9% year-on-year, reflecting the decline in China’s real estate sector.
- Chemical fibre output decreased 3.2% year-on-year, extending a decline that began in April, when output fell for the first time in 22 months. Non-ferrous metal output remained elevated, up 1.6% year-on-year.
- Sulfuric acid output fell by 15.5% due to the continued impacts of shipping disruptions in the Strait of Hormuz, affecting supplies of this key input for phosphate fertiliser production.
The steel and cement industries are the largest CO2 emitters in China, when emissions from their electricity use are included. They are also bellwethers of real estate, infrastructure, and other fixed-asset investments that play an outsized role in China’s emissions and economy. Sulfuric acid and chemical fibre output indicate wider trends in China’s emissions-intensive chemicals sector.
Average daily iron and steel output hit multi-year lows in early September
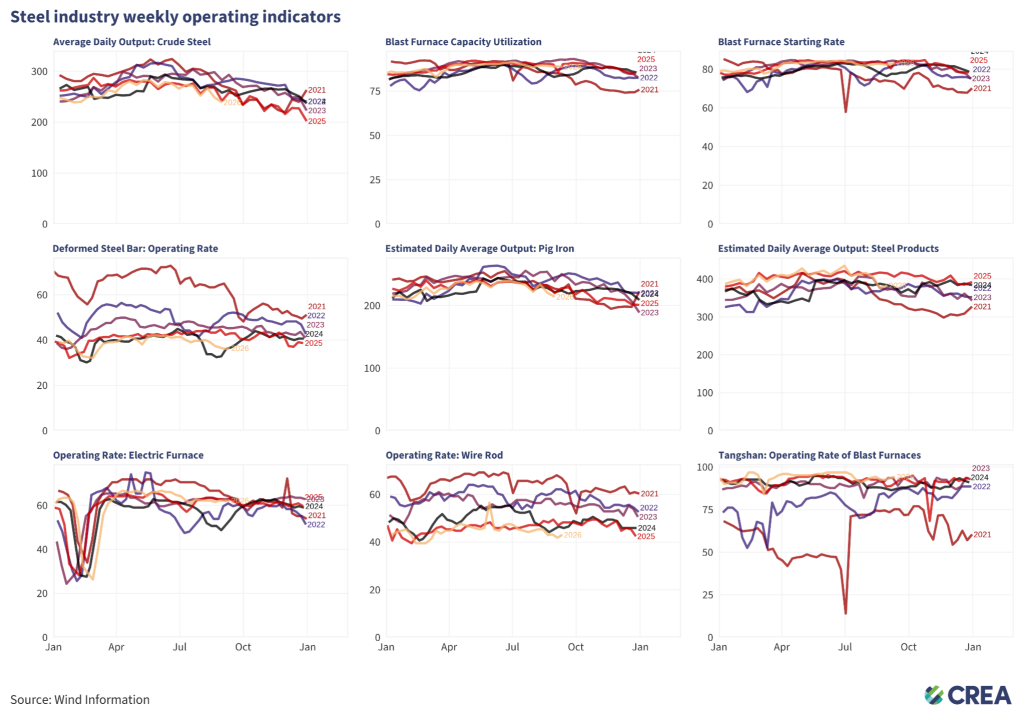
- Blast furnaces for steel production remained active in the second week of September, with a starting rate of 73.6% and utilisation reaching 88.7%. Electric furnace operating rates stayed at 62.8%, slightly below the same period last year.
- Daily pig iron and crude steel output in early September 2026 both fell to their lowest levels for the same period since 2021, while daily steel products output dropped 8% year-on-year, falling back to the 2024 level.
- The operating rate of blast furnaces in Tangshan, China’s ‘steel capital’ and a major industrial source of regional air pollution, reached 94.3% in early September, the highest level in several years.
Hebei Province industrial output is a bellwether of national priorities: when air quality and emissions are the priority, it is the most tightly regulated area due to its impact on Beijing’s pollution levels.
Thermal power additions reach a new record in the first seven months since 2010
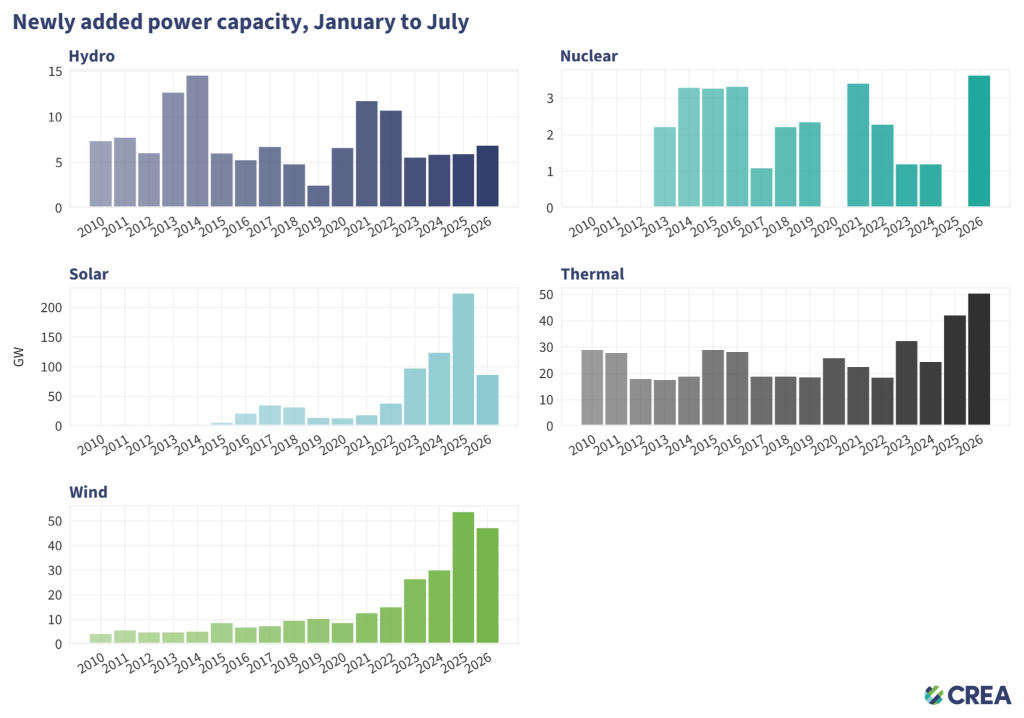
In the first seven months of 2026, China added:
- 86.1 gigawatts (GW) of solar power capacity, down 61% from a very high baseline in 2025 and the lowest level of additions in the first seven months of a year since 2023;
- 47.1 GW of wind power capacity, down 12% from a similarly high baseline last year, but still higher than the 2023-2024 level.
- 50.3 GW of thermal power capacity, up 20% from last year, the highest level in the same period of the last 15 years. 2026 is expected to be one of the highest years on record for new coal power capacity coming online
- 6.8 GW of hydro power capacity, up 16% from last year;
- 3.6 GW of nuclear power capacity, up from 0 GW in the same period last year.
In July 2026 alone, China added:
- 14 GW of solar power capacity, up 27% from July last year;
- 8.5 GW of wind power capacity, up 270% from last year, reflecting a slump in July 2025 following the policy deadline;
- 11.9 GW of thermal power capacity, down 27% from last year;
- 0.8 GW of hydro power capacity, down 59% from last year;
- No new nuclear power capacity, the same as July 2025.
Large-scale clean energy bases took the lead in wind and solar installations
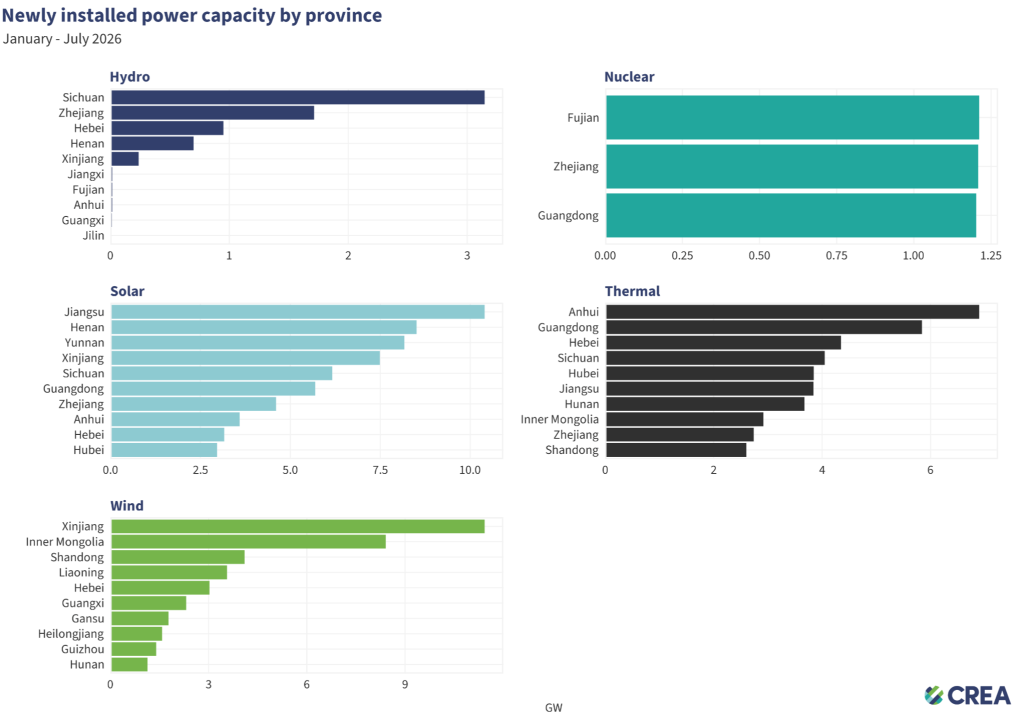
- Solar power installations this year are led by Jiangsu, Henan, Yunnan, and Sichuan. Yunnan and Sichuan’s strong showing is notable, as both are already major hydropower provinces and are set to host new hydro-wind-solar bases under the 15th Five-Year Plan (FYP).
- Wind development was led by Xinjiang, Inner Mongolia, and Shandong. Inner Mongolia and Xinjiang are also part of the large-scale clean energy bases initiative under the 15th FYP.
- Thermal (mainly coal) power additions accelerated in Anhui, Guangdong, Hebei, and Sichuan.
Read more: China Coal Power Biannual Review – H1 2026
Solar production decline continued, as battery production remains robust
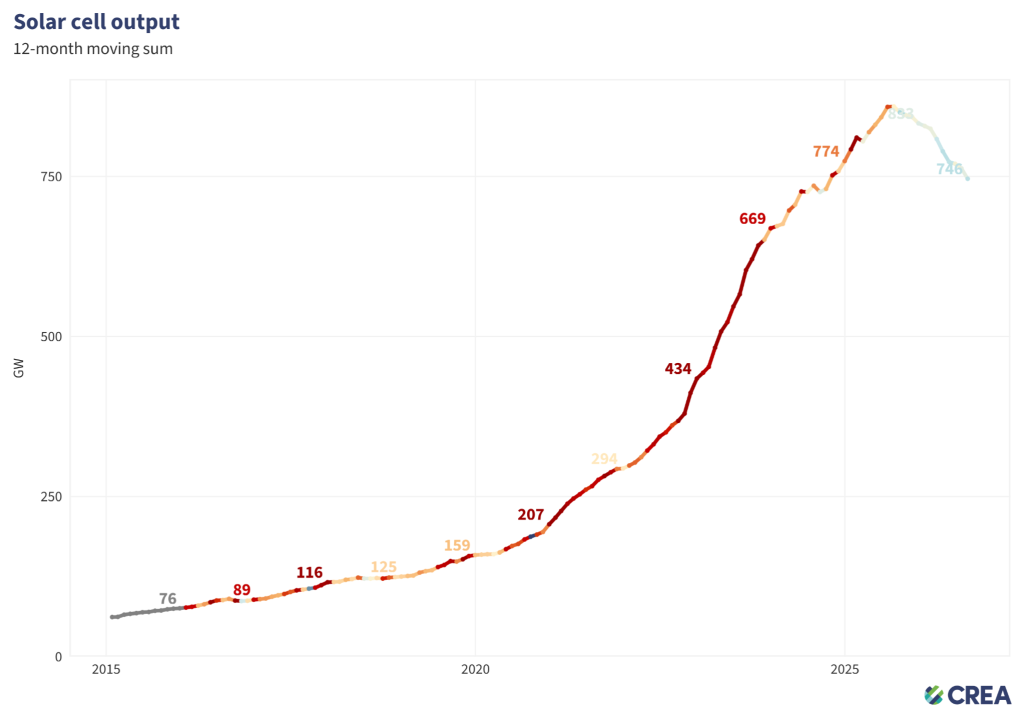
- Solar cell production contracted again in August, falling 13% year-on-year. However, 506 GW of cells were produced in the first eight months of the year, putting 2026 output on track to comfortably exceed the 660 GW of solar capacity installed globally in 2025.
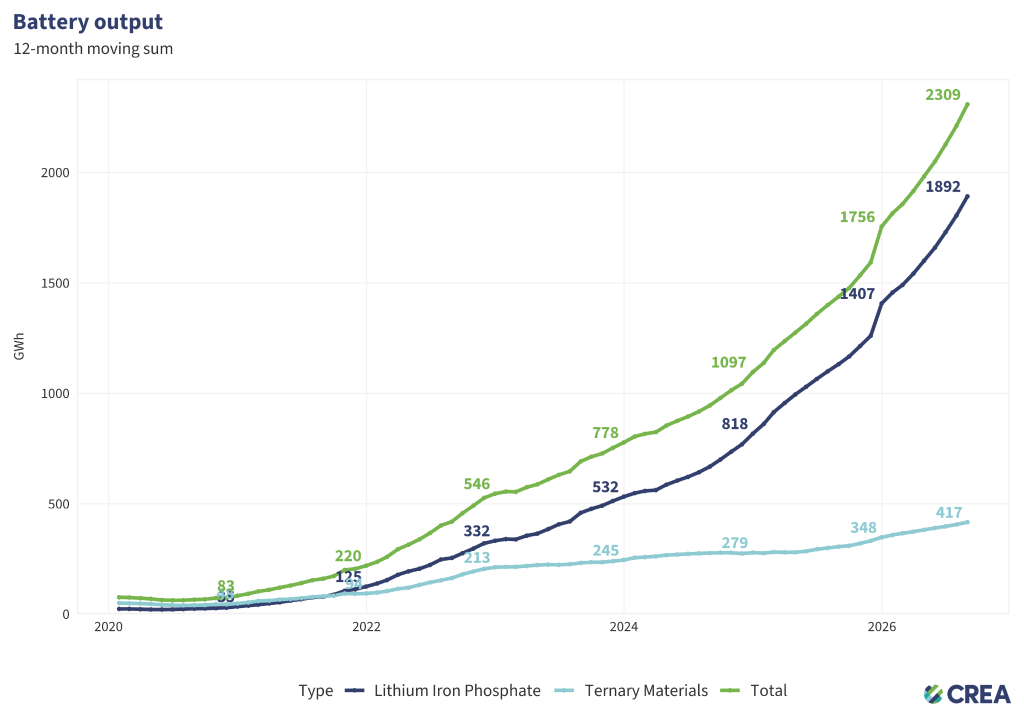
- Battery production reached 237 GWh in August, a 70% increase from a year earlier, driven by robust demand from energy storage and export markets.
NEV exports boom despite weaker domestic sales
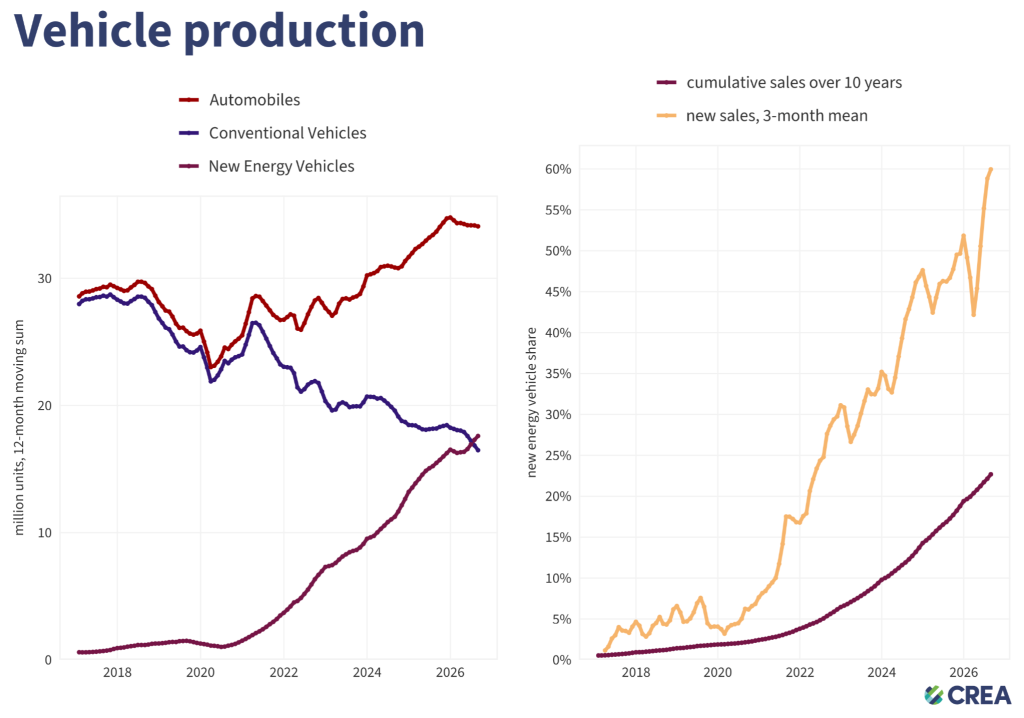
- New Energy Vehicle (NEV) production continued to grow in August, rising 21.9% year-on-year. Production in the first eight months of 2026 was up 11.3%. Overall vehicle production declined 2.7% in August, bringing the share of NEVs to 61% of all vehicles produced.
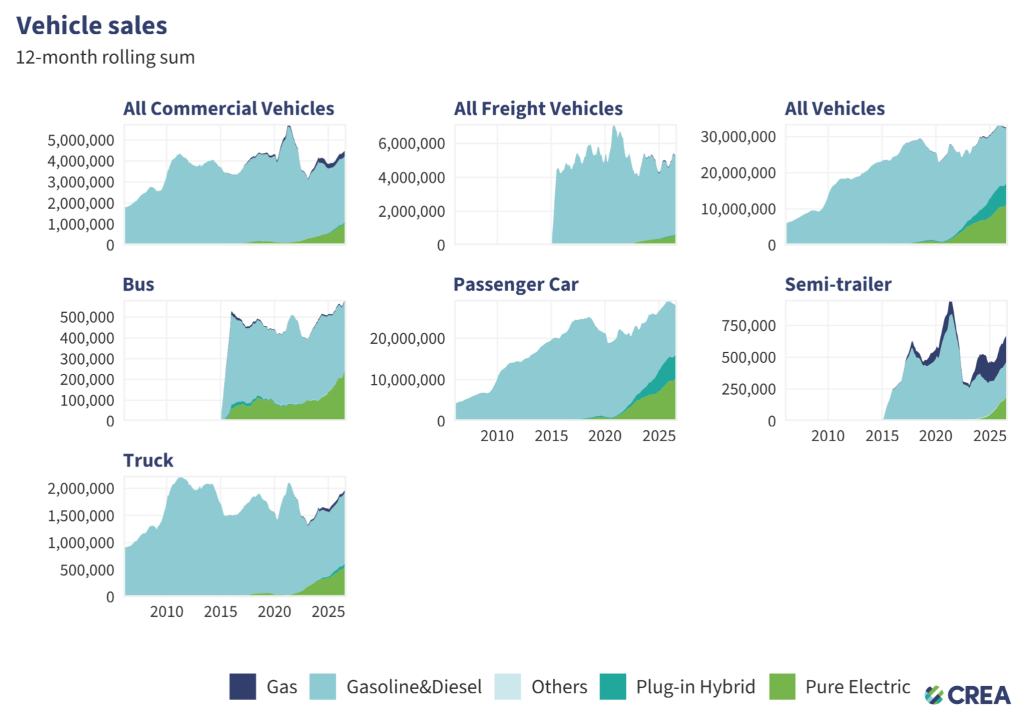
- NEV sales increased 17.8% year-on-year in August, while domestic NEV sales fell 4.6%. NEVs accounted for 65.7% of total domestic vehicle sales. In the first eight months of 2026, domestic NEV sales declined 10.8% year-on-year, largely due to the broader decline in domestic vehicle sales.
- NEV exports surged 130% year-on-year in August 2026. In the first eight months of the year, NEV exports reached 3.44 million units, up 120% year-on-year.
Relevant analysis by CREA:
Analysis: China’s CO2 emissions fall in Q2 2026 due to plummeting oil use
Built for backup, contracted to run: China’s coal support system risks crowding out clean power | China Coal Power Biannual Review H1 2026
China’s new energy plan leaves emissions loose
China’s CO2 climbs 2% in early 2026 due to ‘wasted’ wind and solar
What drove China’s historic drop in power-sector emissions?
China’s new carbon metric leaves Germany-sized gap in its emissions
Reclaiming credibility in China’s steel industry: Climate ambition, financial resilience, and market trust
China’s 15th Five-Year Plan — Implications for climate and energy transition
Analysis: Clean energy drove more than a third of China’s GDP growth in 2025
Analysis: China’s CO2 emissions have now been ‘flat or falling’ for 21 months