
Authors: Luke Wickenden, Daryna Dvornichenko, and Isaac Levi; Data scientist: Panda Rushwood
Russia’s fossil fuel export revenues hit the highest monthly level since December 2022 as seaborne crude earnings and LNG loadings break records
Key findings
- In October 2026, Russia’s fossil fuel export revenues increased 14% month-on-month to EUR 754 mn per day, the highest level since December 2022, while export volumes were broadly unchanged.
- Russia’s crude oil export revenues increased 19% month-on-month to EUR 449 mn per day in October 2026, the highest since June 2022, and volumes increased 6%. Pipeline crude oil export earnings were 6% higher than the previous month, and seaborne crude export revenues rose 23% to EUR 352 mn per day, the highest monthly level in data going back to January 2022.
- In October 2026, revenue from seaborne oil product exports rose 4% month-on-month to EUR 85 mn per day, still the third-lowest monthly level since Russia’s full-scale invasion, while export volumes fell 8%.
- In October 2026, LNG export revenues increased 3% month-on-month to EUR 77 mn per day, the highest level since January 2023.
- In October 2026, EU imports of Russian LNG fell 10% month-on-month, with French imports down 13%, while Spain received 138 thousand tonnes after none in September. Belgium imported no Russian LNG for the third consecutive month.
- In October 2026, China remained the world’s largest importer of Russian fossil fuels, and both China (EUR 10.7 bn) and India (EUR 6.4 bn) made their highest monthly purchases in data going back to January 2022. The EU remained the third-largest importer, ahead of Turkiye.
- In October 2026, China unloaded its second-highest monthly volume of Russian LNG on record, including its highest-ever monthly volume from the sanctioned Arctic LNG 2 project.
- South Korea was the fifth-largest importer of Russian fossil fuels in October 2026, purchasing EUR 488 mn, with LNG accounting for 54% of the total.
- EU imports of Russian LNG fell by just 1.2% year-on-year in the six months following the REPowerEU short-term contract ban, with cargoes largely redistributed among member states.
- Despite the EU’s ban on oil products made from Russian crude, twelve shipments from refineries processing Russian crude were unloaded at EU ports in October 2026, up from seven in September.
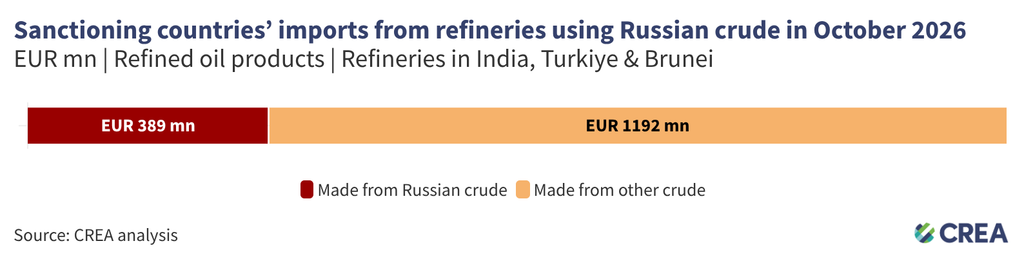
- Refineries in India, Turkiye, and Brunei that use Russian crude exported EUR 1.6 bn of oil products to sanctioning countries in October 2026, a 21% rise in export volume month-on-month.
- In October 2026, 60% of Russia’s seaborne oil was transported by sanctioned ‘shadow’ tankers. A further 37% of the volume was transported by G7+ owned or insured tankers. The remainder was transported by non-sanctioned ‘shadow’ tankers.
- Forty ‘shadow’ vessels were operating under false flags at the end of October 2026, down from 112 at the end of October 2025. Falsely flagged tankers carried only 3% of the Russian oil delivered by the ‘shadow’ fleet in October 2026.
- In October 2026, 62 Russian-flagged ‘shadow’ tankers delivered 47% of the Russian oil carried by the ‘shadow’ fleet, up from 20 tankers and 6% in October 2025, making the Russian flag the largest in the ‘shadow’ fleet.
- A USD 30 per barrel crude oil price cap and lower oil product caps, if fully enforced, would have cut Russia’s seaborne oil export revenues by 25% (EUR 3.4 bn) in October 2026.
Trends in total export revenues
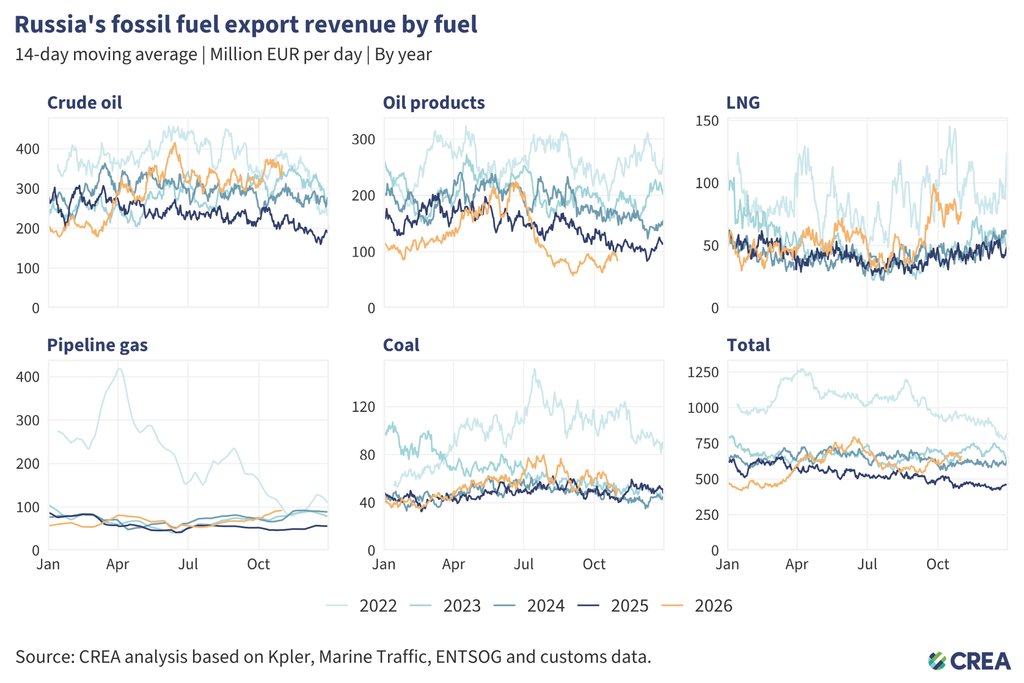
- In October 2026, Russia’s fossil fuel export revenues increased 14% month-on-month to EUR 754 mn per day, the highest level since December 2022, while export volumes were broadly unchanged.
- Russia’s crude oil export revenues increased 19% month-on-month to EUR 449 mn per day in October 2026, the highest since June 2022, and volumes increased 6%. Pipeline crude oil export earnings were 6% higher than the previous month, and seaborne crude export revenues rose 23% to EUR 352 mn per day, the highest monthly level in data going back to January 2022.
- Revenue from seaborne oil product exports unloaded at their destination ports rose 4% month-on-month to EUR 85 mn per day in October 2026, while export volumes fell 8%.
- Oil product loadings at Russian ports increased by 24% month-on-month in October 2026, marking a recovery, although they still remained 38% below October 2025 levels.
- Quantities of diesel loaded at Russian ports rose threefold in October 2026, while Russia extended its diesel export ban until 31 January 2027, retaining exemptions that allow selected companies to export under government quotas. Despite significant media attention on the Trump–Putin diesel agreement, which stated that Russia would supply over 300,000 tonnes of diesel to American and global markets, no shipments of Russian diesel were unloaded at US ports in October 2026. Some shipments of Russian diesel predicted as heading towards the US have in fact changed destination, and at the time of publication, no shipments of Russian oil products have been unloaded at US ports.
- Russia’s recovery in oil product exports remains uneven. Tuapse, Russia’s fourth-largest oil product export port before the full-scale invasion, has faced sustained drone attacks since May and has loaded no oil products at all since August, after only a token volume in July.
- Crude oil loadings at Russia’s Baltic Sea port of Ust-Luga recovered, rising 17% month-on-month in October. Activity at the Novorossiysk oil terminal is also increasing: oil product exports from the port rose 30% month-on-month, though from a very low base, and still remain around 80% below October 2025 levels.
- Liquefied natural gas (LNG) export revenues from unloaded cargoes rose 3% to EUR 77 mn per day in October 2026, while volumes fell 4% month-on-month. By contrast, loaded Russian LNG volumes increased 5% month-on-month, as higher loadings from Russia’s Yamal LNG (+17%) and the sanctioned Arctic LNG 2 project (+20%) more than offset a 13% decline at Kamchatka and a halt in loadings at Portovaya and Murmansk.
- Pipeline gas export revenues rose by 23% to EUR 88 mn per day in October 2026, and export volumes increased 5% month-on-month. Pipeline gas earned more than seaborne oil products for the first time since May 2022.
- Russia’s coal export revenues fell by 3% month-on-month to EUR 56 mn per day in October 2026.
- Russia’s mineral extraction tax (MET) receipts from crude oil reached 979.3 billion rubles in October, up 42% month-on-month and the highest level since February 2024, driven by higher oil prices amid the war in the Middle East.
Who is buying Russia’s fossil fuels?
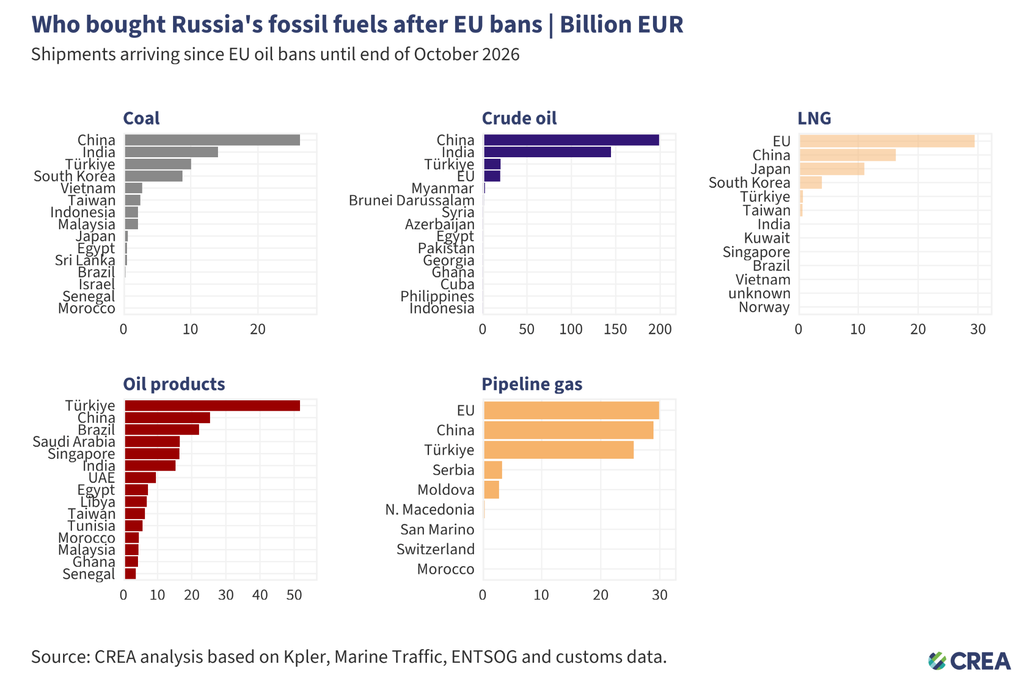
- Russia’s fossil fuel exports remain highly concentrated, with China dominating purchases of coal and crude oil, Turkiye leading purchases of oil products, and the EU remaining the largest buyer of LNG and pipeline gas — showing Moscow’s dependence on a narrow set of key customers.
- Coal: From 5 February 2023 until the end of October 2026, China purchased 37% of all Russian coal exports. India (20%), Turkiye (14%), South Korea (12%), and Vietnam (4%) round out the top five buyers’ list.
- Crude oil: China has bought 50% of Russia’s crude exports, followed by India (37%), Turkiye (5%), and the EU (5%).
- Oil products: Turkiye, the largest buyer, has purchased 26% of Russia’s oil product exports, followed by China (13%), Brazil (11%), Saudi Arabia (8%), and Singapore (8%).
- LNG: The EU remains the largest buyer of Russian LNG, accounting for almost half (47%) of Russia’s total LNG exports, followed by China (26%), Japan (18%), and South Korea (6%).
- Pipeline gas: The EU is the largest buyer, purchasing 33% of Russia’s pipeline gas exports, followed closely by China (32%) and Turkiye (28%).
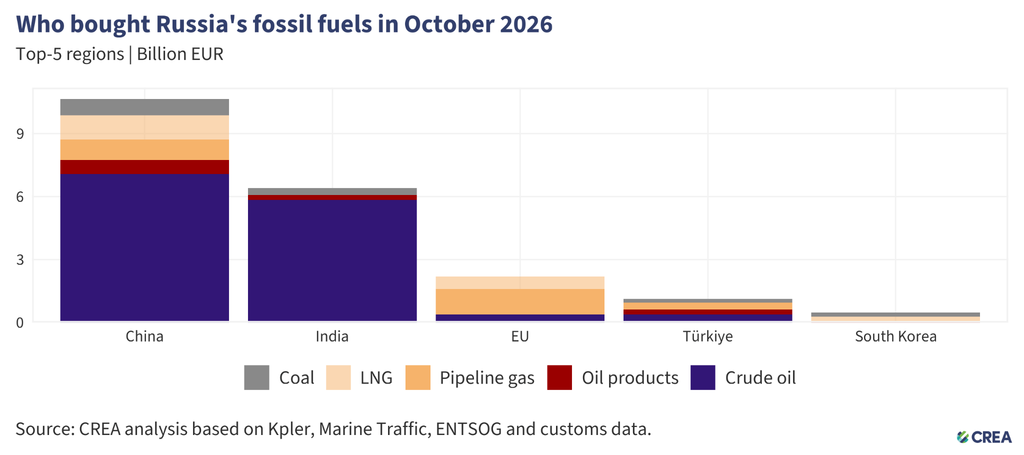
- In October 2026, China remained the largest global buyer of Russian fossil fuels, accounting for 51% (EUR 10.7 bn) of Russia’s export revenues from the top five importers, its highest monthly total in data going back to January 2022. Crude oil accounted for two-thirds (EUR 7.1 bn) of China’s purchases, followed by LNG (EUR 1.2 bn), pipeline gas (EUR 979 mn), coal (EUR 778 mn), and oil products (EUR 674 mn).
- China unloaded 2% higher quantities of seaborne Russian crude in October 2026 month-on-month. East Siberia–Pacific Ocean (ESPO) grade crude, loaded at the Pacific port of Nakhodka, already accounting for more than half of Russian crude imports in September, rose further in October to 64%. The next two largest import grades, Sokol and Urals, fell by 20% and 66%, respectively.
- In October 2026, Rizhao became China’s largest import hub for Russian seaborne crude, with unloadings up 83% month-on-month, while imports by the UK and EU-sanctioned Shandong Yulong installation rose 32%. By contrast, unloadings at Dongjiakou Oil Terminal and Dongying fell by 22% and 19%, respectively.
- In October 2026, China unloaded its second-highest monthly volume of Russian LNG on record, including its highest-ever monthly volume from the sanctioned Arctic LNG 2 project.
- India was the second-largest buyer of Russian fossil fuels in October 2026, importing a total of EUR 6.4 bn of Russian hydrocarbons, its highest monthly total in data going back to January 2022. Crude oil constituted 91% of India’s purchases, totalling EUR 5.8 bn. Coal (EUR 333 mn) and oil products (EUR 232 mn) constituted the remainder of its monthly Russian imports.
- India’s imports of Russian crude oil rose in October 2026, up 10% month-on-month. Russian crude imports rose at all three of India’s largest importing refineries: Vadinar (up 12% month-on-month), Jamnagar (up 22%), and Paradip (up 28%). This increase has once again made the Jamnagar refinery the biggest importer of seaborne Russian crude.
- The EU was the third-largest buyer of Russian fossil fuels, accounting for 11% (EUR 2.2 bn) of Russia’s export revenues from the top five importers in October 2026.
- Pipeline gas accounted for 55% of the EU’s imports (EUR 1.2 bn), and LNG accounted for 28% (EUR 606 mn). Crude oil accounted for the remaining 17% (EUR 384 mn), all of which was transported through the Druzhba pipeline to Slovakia and Hungary.
- Turkiye was the fourth-largest importer, purchasing EUR 1.1 bn of Russian hydrocarbons in October 2026. Crude oil accounted for the largest share at 34% (EUR 388 mn), followed by pipeline gas (EUR 332 mn), oil products (EUR 238 mn), and finally coal (EUR 171 mn).
- Turkiye’s imports of Russian oil products fell 38% month-on-month in October 2026 to 292 thousand tonnes, the lowest monthly volume going back to January 2022. Despite this, seaborne crude unloadings increased by 67% month-on-month.
- South Korea was the fifth-largest importer of Russian fossil fuels in October, purchasing EUR 488 mn. LNG accounted for more than half (54%) of South Korea’s imports; coal (EUR 202 mn) and oil products (EUR 21 mn) accounted for the remainder.
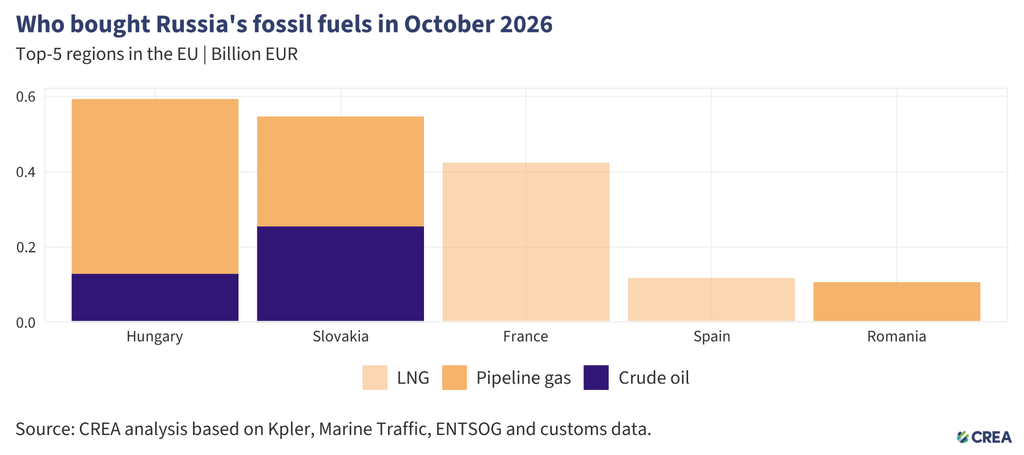
- In October 2026, the five largest EU importers of Russian fossil fuels paid Russia a combined EUR 1.8 bn. Natural gas (pipeline and LNG) — partially sanctioned by the EU — accounted for 79% of the value of imports from the five largest buyers. The five largest EU importers purchased EUR 1.4 bn of Russian natural gas, comprising EUR 864 mn of pipeline gas and EUR 543 mn of LNG, as well as EUR 384 mn of crude oil via the Druzhba pipeline.
- In October 2026, EU imports of Russian LNG fell 10% month-on-month, with French imports down 13%, while Spain received 138 thousand tonnes after none in September.
- In October, Hungary was the EU’s largest buyer of Russian fossil fuels, importing EUR 594 mn, of which EUR 464 mn was pipeline gas and EUR 129 mn was crude oil delivered via the Druzhba pipeline.
- Slovakia was the second-largest EU importer of Russian fossil fuels in October, with purchases split almost evenly between pipeline gas (EUR 292 mn) and crude oil (EUR 255 mn).
- France was the EU’s third-largest importer in October, importing EUR 424 mn of Russian LNG.
- Spain was the fourth-largest EU importer of Russian fossil fuels in October, purchasing EUR 118 mn in LNG.
- Romania was the fifth-largest EU importer of Russian fossil fuels in October, purchasing EUR 107 mn of pipeline gas.
- In October 2026, EU total LNG imports rose, with 70% of the unloaded cargoes originating from the US.
- Despite the EU’s ban on imports of oil products made from Russian crude, which came into force on 21 January 2026, twelve shipments of oil products from refineries using Russian crude — identified as high risk according to EU guidance — were unloaded at EU ports in October. This was an increase from the number of vessels unloaded in September 2026.
- Ten of these shipments departed from India’s Jamnagar refinery, while two departed from Turkiye’s STAR refinery.
- Italy and Romania were the largest recipients in October, unloading three shipments each, followed by Greece, the Netherlands, Spain, Belgium, France, and Germany. A further two shipments were unloaded at the port of Kalecik in Northern Cyprus, where EU law does not apply, so they fall outside the ban and are not counted here. The application of EU law is suspended in northern Cyprus under Article 1(1) of Protocol No 10 to the 2003 Act of Accession because the government of the Republic of Cyprus does not exercise effective control there. However, this does not provide a blanket exemption from EU sanctions for EU nationals or companies involved in transactions with Kalecik port.
- Enforcement agencies in Member States must investigate shipments of oil products imported from refineries processing Russian crude or from ports connected to these refineries, to prevent Russian oil molecules from entering the bloc and thereby violating the EU’s ban.
- Refineries in India, Turkiye, and Brunei that use Russian crude exported EUR 1.6 bn of oil products to sanctioning countries in October 2026. The destinations include the EU (EUR 1.2 bn), Australia (EUR 271 mn), the US (EUR 94 mn), and New Zealand (EUR 23 mn). An estimated EUR 389 mn of these products were refined from Russian crude.
- There was a 21% month-on-month increase in the volume of oil product exports from these refineries reported as destined for ports in sanctioning countries.
- Exports of oil products reported as destined for EU ports from refineries running on Russian crude rose 41% in volume terms month-on-month in October. Exports headed to Australia rose 18% month-on-month, while those headed to the US fell 48%.
- Exports travelling to the US in October came from India’s Jamnagar refinery (EUR 94 mn). Between August and October 2026, 30% of the Jamnagar refinery’s crude imports came from Russia.
- The Tupras Izmit refinery in Turkiye, which exported products destined for the EU in October 2026, imported 53% of its Russian crude oil from Russia between August and October this year.
- In October 2026, 76% of crude oil imports for Brunei’s Hengyi refinery came from unknown sources via ship-to-ship transfers off the east coast of Peninsular Malaysia, near the Singapore Strait, according to Kpler data. The largest export market for oil products from the Hengyi refinery is Australia.
- The Kulevi port in Georgia, which is connected to the Kulevi refinery via pipeline, did not import any seaborne Russian crude in October 2026. In October, 100% of the Kulevi port’s seaborne crude oil imports came from Libya. The Georgian port of Kulevi has stated that it will no longer accept Russian oil as of August or September this year.
| EU imports of Russian LNG fall just 1.2% year-on-year in the six months following the REPowerEU ban on short-term imports |
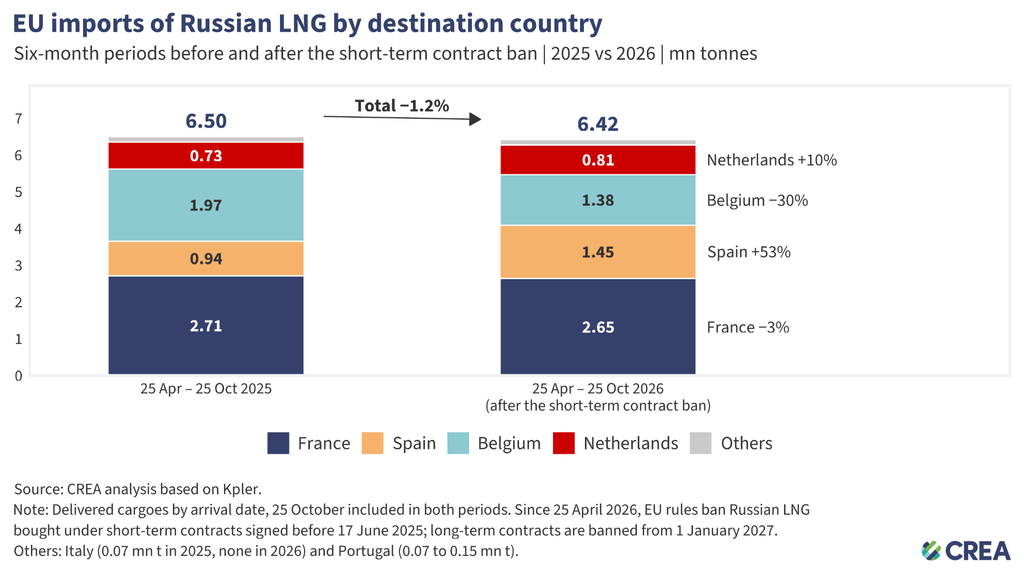
| Six months after the EU’s ban on short-term contracts for Russian liquefied natural gas (LNG) came into force, EU imports of Russian LNG have fallen by just 1.2%. Rather than leaving the European market, cargoes have been redistributed among member states.The REPowerEU Regulation (EU) 2026/261 was adopted by the Council on 26 January 2026. It introduces a general prohibition on imports of Russian pipeline gas and LNG, with transitional periods for contracts concluded before 17 June 2025. Imports under short-term LNG contracts, those lasting up to one year, were banned from 25 April 2026, and short-term pipeline contracts followed on 17 June 2026. Long-term LNG contracts are permitted until 1 January 2027 and long-term pipeline contracts until 30 September 2027. Imports allowed during these transitional periods require prior authorisation from national authorities, who must first verify the origin of the gas. The first deadline has made almost no difference to the EU imports of Russian LNG. In the six-month period following the short-term contract ban, between 25 April and 25 October 2026, EU member states imported 6.42 million tonnes (Mt) of Russian LNG across 89 cargoes valued at EUR 4.1 bn. In the same period of 2025, they imported 6.50 Mt of LNG, valued at EUR 3.1 bn, across 90 cargoes. EU import volumes fell by 1.2%, and cargo numbers declined by just one, while higher prices pushed the import value up by about a third. All cargoes of Russian LNG in both periods were loaded at the Yamal installation. ACER, the EU energy regulator, found that no authorisation requests were made for short-term contracts between January and early June 2026. Every authorised import was linked to long-term contracts, which total 20–32 bcm a year. ACER also reported that Russian LNG imports rose 17% year-on-year between mid-March and the end of May, as buyers brought deliveries forward ahead of the deadlines. In effect, it appears that the 25 April deadline banned a type of contract that was hardly being used. Unless further action is taken, Russian LNG will continue flowing into the EU at nearly unchanged rates until the long-term ban takes effect on 1 January 2027. At the country level, France remained the largest importer over the six months to 25 October 2026, receiving 2.65 Mt, down 3% year-on-year, and accounting for 41% of total EU volumes. Within France, imports moved between terminals: Dunkerque rose 21% to 1.64 Mt, while Montoir fell 26% to 1.00 Mt. Spain recorded the largest increase, with imports up 53% to 1.45 Mt, overtaking Belgium as the second-largest importer. Most of Spain’s growth went through Bilbao, where arrivals rose from four cargoes to eleven (0.29 Mt to 0.80 Mt), and Sagunto and Cartagena each received Russian LNG in 2026 after none in 2025. Belgium had the steepest decline among the major importers, with volumes falling 30% from 1.97 Mt between 25 April and 25 October 2025 to 1.38 Mt in the same period of 2026, all quantities unloaded at Zeebrugge, where arrivals fell from 27 cargoes to 19. No cargoes of Russian LNG were unloaded at Belgian ports between August and October 2026. Over the same period, the Netherlands increased its imports by 10%, from 0.73 Mt to 0.81 Mt, at Rotterdam’s Gate terminal. Portugal doubled its imports to 0.15 Mt at Sines, receiving two cargoes compared with one a year earlier. Italy received no Russian LNG in 2026, down from a single 0.07 Mt cargo at the Ravenna FSRU (Floating Storage and Regasification Unit) in 2025. France, Spain and Belgium together received 85% of the EU’s Russian LNG over the six months. The first phase of the REPowerEU phase-out has so far done little more than move Russian cargoes between European ports. Russia’s EU LNG revenue will remain largely intact until the long-term contract deadline on 1 January 2027, which will be the real test of the regulation. Until then, member states should apply the authorisation and origin checks rigorously so that existing contracts cannot be amended, extended or relabelled to keep Russian cargoes arriving. |
How are oil prices changing?
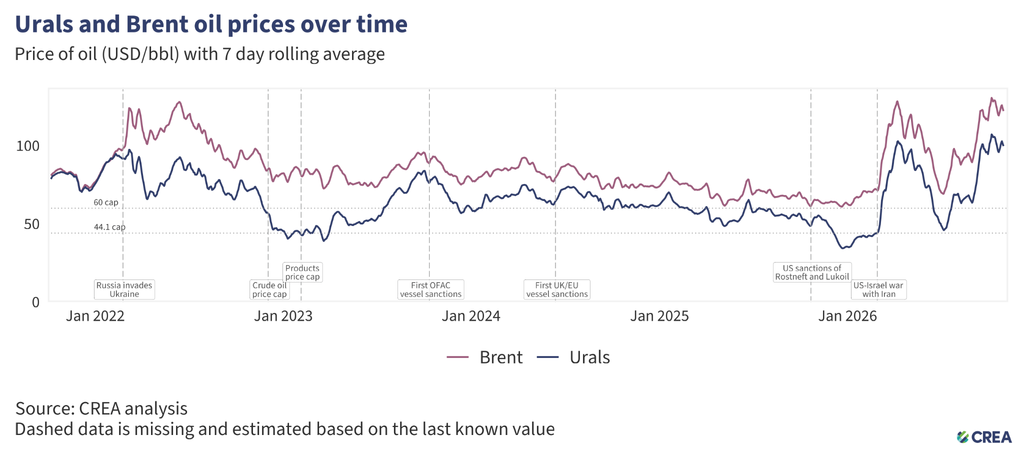
- In October 2026, the average price of Russia’s Urals-grade crude rose by 13% month-on-month to USD 101.7 per barrel, the highest monthly average in data going back to October 2021 and more than double the EU and UK price cap of USD 44.1 per barrel, which took effect on 1 February 2026 and has been capped at the same level under the EU’s 21st sanctions package.
- Global fossil fuel prices remained high in October despite month-on-month increases of 9% in oil volume and 15% in LNG volume transported through the Strait of Hormuz, as measured by detected vessel crossings. These volumes remained well below levels recorded before the US and Israeli strikes on Iran.
- The Hormuz energy crisis has delivered a substantial boost to Russia’s fossil fuel export earnings. CREA’s recent analysis estimates that, in the six months since the US–Israel strikes on Iran began, higher oil and gas prices have increased Russia’s seaborne export revenues by an estimated USD 35.9 bn (equivalent to EUR 31 bn).
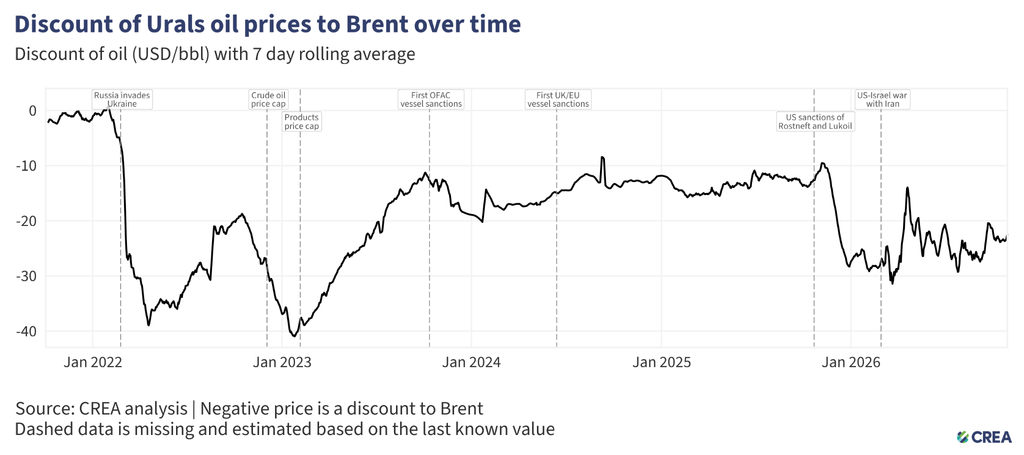
- In October 2026, the price discount on Urals-grade crude oil relative to the global benchmark Brent averaged USD 23 per barrel (19%), compared with USD 24 per barrel (21%) in September 2026.
Sanctioned tankers carry the majority of Russian crude despite G7+ sanctions
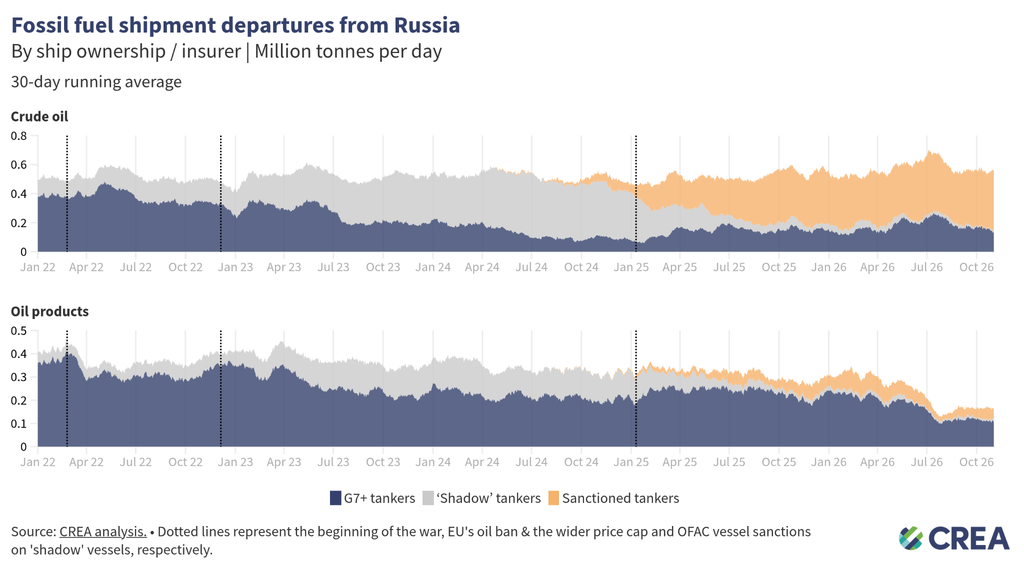
- In October 2026, 60% of Russia’s seaborne oil was transported by sanctioned ‘shadow’ tankers. A further 37% of the volume was transported by G7+ tankers. The remainder was transported by non-sanctioned ‘shadow’ tankers.
- G7+ tankers transported 29% of Russian crude oil exports in October, while non-sanctioned ‘shadow’ tankers accounted for 2% of the total. The largest share, 69%, was carried by sanctioned ‘shadow’ tankers.
- For oil products, Russia’s dependence on G7+ tankers is higher; these tankers transported 68% of Russian oil products in October. Sanctioned ‘shadow’ tankers carried 27% of the total volume of Russian oil products, while non-sanctioned ‘shadow’ tankers accounted for the remainder.
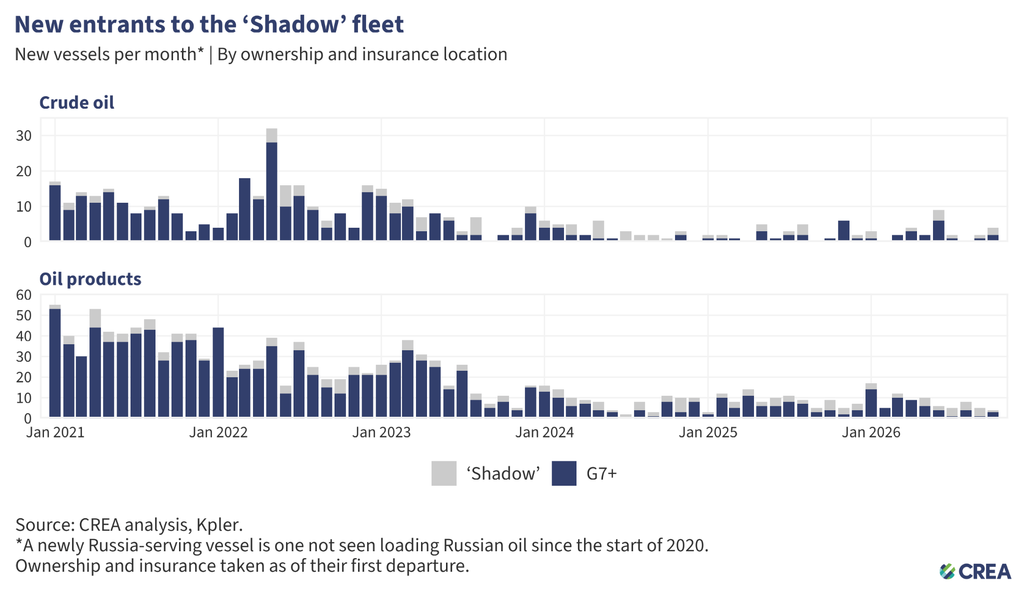
- In October 2026, eight new vessels entered the Russian oil trade, none of which had previously loaded Russian oil at any point since the start of our analysis period in 2020. This total is below the average (roughly 11 new vessels per month) over the past 12 months. Five of those eight newly Russia-serving vessels were owned or insured by the G7+ at the time of loading.
- Newly Russia-serving ‘shadow’ fleet vessels (with no ownership or insurance registered in sanctioning countries) remained low throughout 2026, never exceeding five per month, and fell to three in October 2026.
- In October 2026, four vessels transported Russian oil products for the first time since 2020, and three were owned or insured by a G7+ country at the time of loading.
- In October 2026, four tankers transported Russian crude oil for the first time since 2020; two of them were owned or insured in a G7+ jurisdiction.
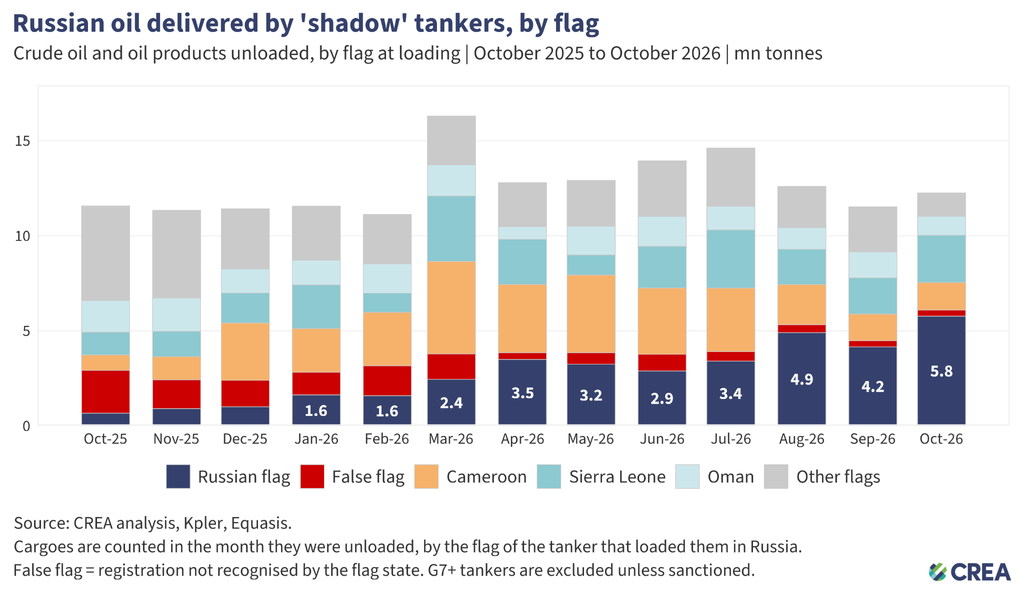
Since our September 2026 report, this section tracks the flags of the entire ‘shadow’ fleet rather than false flags alone.
- In October 2026, 62 tankers sailing under the Russian flag delivered 47% (5.8 mn tonnes) of the Russian crude oil and oil products carried by ‘shadow’ tankers, up from 20 tankers and 6% (0.7 mn tonnes) in October 2025. The Russian flag has been the largest single flag in the ‘shadow’ fleet since July 2026.
- At the end of October 2026, 393 tankers that had carried Russian oil were sailing under the Russian flag. Of these, 183 joined the Russian registry after January 2025, and 109 of those had previously flown a false flag.
- Sierra Leone was the second-largest flag in October 2026, carrying 20% (2.5 mn tonnes) of the oil delivered by ‘shadow’ tankers, double its 10% share in October 2025. Cameroon (12%) and Oman (8%) were the next-largest flags.
- Russian-flagged tankers lifted 44% of the oil loaded by ‘shadow’ tankers at Russian ports in October 2026, cargoes that will largely be unloaded in November.
- Falsely flagged tankers delivered 3% (0.3 mn tonnes) of the oil carried by ‘shadow’ tankers in October 2026, and 40 ‘shadow’ vessels were operating under false flags at the end of the month.
- Two vessels suspected of sailing under false flags were detained in October 2026. On 12 October, the French Navy intercepted the sanctioned tanker DF Peak in the Indian Ocean, which was reportedly carrying Russian crude oil under a false Benin flag. Norwegian authorities detained the sanctioned cargo ship Ya Qing Hai Yang, which had previously carried equipment for the Arctic LNG 2 project, after finding that it lacked a valid flag registration.
‘Shadow’ tankers pose significant risks to ecology and the impact of sanctions
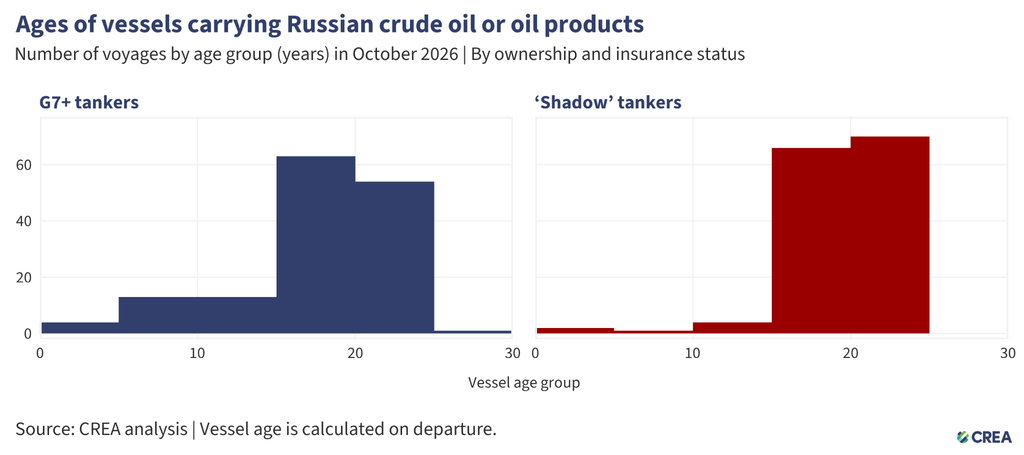
- In October 2026, 294 cargoes of Russian crude oil and oil products were delivered. Of these, 159 were carried by ‘shadow’ tankers, and the remaining 135 by G7+ owned or insured tankers. Additionally, half (80 in total) of the cargoes on ‘shadow’ tankers were carried by vessels at least 20 years old.
- Older ‘shadow’ tankers transporting Russian oil through EU waters pose environmental and financial risks due to their age, poor maintenance, and inadequate protection and indemnity (P&I) insurance. In the event of an oil spill or accident, coastal states may face significant cleanup costs and damage to their marine ecosystems.
- The cost of cleanup and compensation from an oil spill by tankers with dubious insurance could amount to over EUR 1 bn for taxpayers in coastal countries.
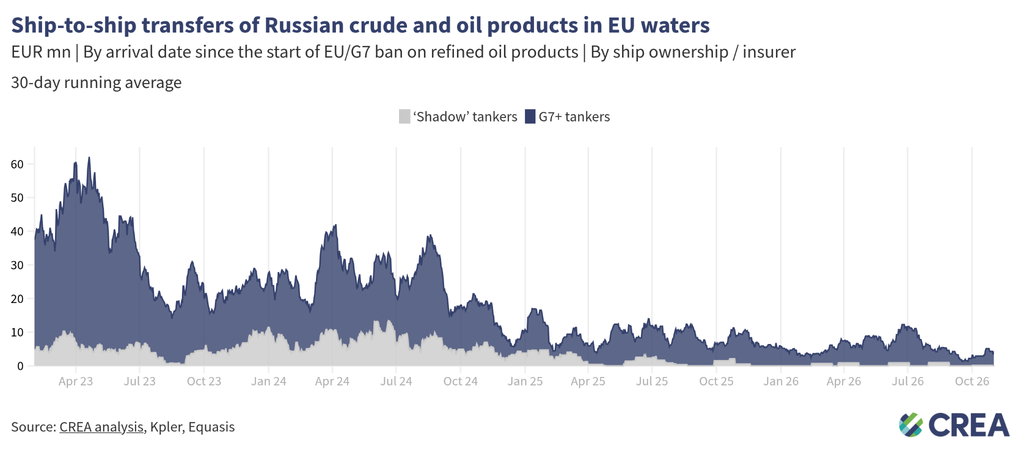
- In October 2026, an estimated EUR 71 mn worth of Russian oil was transferred across five ship-to-ship (STS) transfers in EU waters.
- STS transfers of Russian oil in EU waters were conducted in Spanish (94%) and Polish waters (6%). G7+ tankers carried four of the five transfers.
- Daily transfers averaged EUR 2.3 mn in October 2026.
- Four of the five STS transfers in EU waters in October 2026 involved oil products, all of which occurred in Spanish waters. The fifth was a cargo of Kaliningrad crude oil, transferred in Polish waters.
How can Ukraine’s allies tighten the screws?
Russia’s fossil fuel export revenues have fallen since the sanctions were implemented, subsequently constricting Putin’s ability to fund his full-scale invasion of Ukraine. However, much more should be done to limit Russia’s export earnings and constrain the funding of the Kremlin’s war chest.
Lower the oil price cap to a baseline that tightens Russian revenues
The oil price cap policy has failed to impose a durable constraint on Russian crude export earnings, working only intermittently and selectively for Urals while leaving other grades and export channels largely unaffected. Urals prices have fallen below the former USD 60-per-barrel cap only intermittently, mainly in the first half of 2023 and from March 2025 to February 2026, and averaged USD 102 per barrel in October 2026. The cap was lowered to USD 44.1 per barrel on 1 February 2026 and subsequently frozen at that level under the EU’s 21st sanctions package. Meanwhile, ESPO-grade crude has consistently traded above both price cap levels because of strong demand from China and other Pacific markets.
G7+ sanctions have focused on Russian revenues rather than on restricting Russian export volumes — aimed at keeping Russian barrels flowing in global markets and easing fears of supply constraints. Policies such as the price cap are mainly aimed at reducing the price at which Russia could sell their oil.
In January 2026, as Russian oil prices fell sharply due to market oversupply, the EU proposed a ban on maritime services that facilitate Russia’s crude oil exports. Subsequently, in April 2026, the EU adopted its 20th sanctions package, which includes the basis for a future maritime services ban on Russian crude oil and petroleum products; however, it will be implemented only if an agreement is reached with the G7 and the Price Cap Coalition members. The maritime services ban would have, for the first time, targeted Russian oil export volumes and aimed at shrinking the tanker capacity required to transport Russia’s oil globally.
A massive spike in oil prices following reduced flows of fossil fuel shipments through the Strait of Hormuz has prompted a rethink of this policy to avoid creating further supply crunches in global markets. Therefore, in the face of the current energy crisis of 2026, CREA recommends that the price cap coalition either fix the price cap policy to a base level that severely restricts Russian revenues or implement a value-based sanction, such as a tax or surcharge on the use of Western maritime services for transporting Russia’s fossil fuels. A tax imposed by sanctioning countries on the use of Western maritime services to transport Russian crude oil and petroleum products could leverage their influence over trade to reduce Russian exporters’ profits, make Russian oil less commercially attractive, and generate revenue that could be used to support Ukraine.
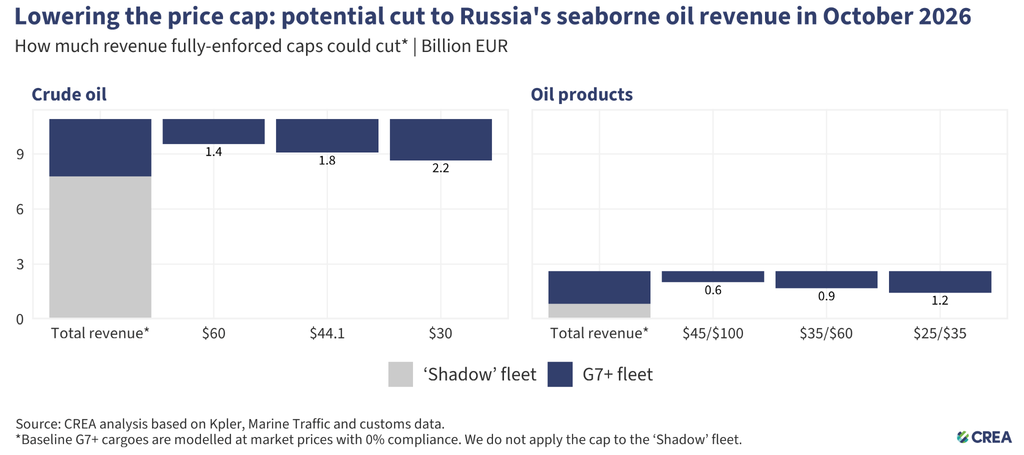
Note: CREA models price cap scenarios using the observed G7+ share of the tanker fleet transporting Russian crude oil and oil products. From the September 2026 edition, crude oil and oil product caps are modelled separately, so the figures below are not directly comparable with those in earlier editions. The two oil product price caps apply to products classified as trading at a premium or a discount to crude oil.
- CREA recommends that the price cap for crude oil be set at a lower level of USD 30 per barrel — still well above Russia’s production cost, which averages USD 15 per barrel. Had a USD 30 per barrel cap been fully enforced on G7+ tankers, Russia’s total seaborne crude oil export revenues would have been 21% (EUR 2.2 bn) lower in October 2026. Since the EU’s ban on Russian crude oil took effect in December 2022, the same cap would have cut these revenues by 18% (EUR 53 bn). By comparison, full enforcement of the current USD 44.1 per barrel cap would have cut Russia’s seaborne crude oil export revenues by 17% (EUR 1.8 bn) in October 2026, and the former USD 60 per barrel cap by 12% (EUR 1.4 bn). Because the cap applies only to oil carried on G7+ tankers, which carried 29% of Russia’s seaborne crude by value in October 2026, most crude revenue lies beyond its reach.
- CREA also recommends lowering the oil product price caps, which have remained unchanged since they were introduced in February 2023 at USD 100 per barrel for products that trade at a premium to crude oil and USD 45 per barrel for those that trade at a discount. Caps of USD 35 and USD 25 per barrel, respectively, would have cut Russia’s seaborne oil product export revenues by 45% (EUR 1.2 bn) in October 2026, and by 43% (EUR 97 bn) since the EU’s ban on Russian oil products took effect in February 2023. An intermediate option of USD 60 per barrel for premium products and USD 35 per barrel for discounted products would have cut Russian oil product export earnings by 36% (EUR 0.9 bn) in October 2026, compared with 23% (EUR 602 mn) under full enforcement of the current caps. Policymakers should not overlook their leverage over the transportation of these products, as G7+ owned or insured tankers carried 68% of Russia’s seaborne oil product exports in October 2026, compared with 29% of its seaborne crude oil exports.
- Together, the lower crude oil and oil product caps would have reduced Russia’s total seaborne oil export revenues by 25% (EUR 3.4 bn) in October 2026, and by 29% (EUR 150 bn) since the bans took effect.
- Lowering the price cap would be deflationary, reducing Russia’s oil export prices and inducing more production from Russia to make up for the drop in revenue.
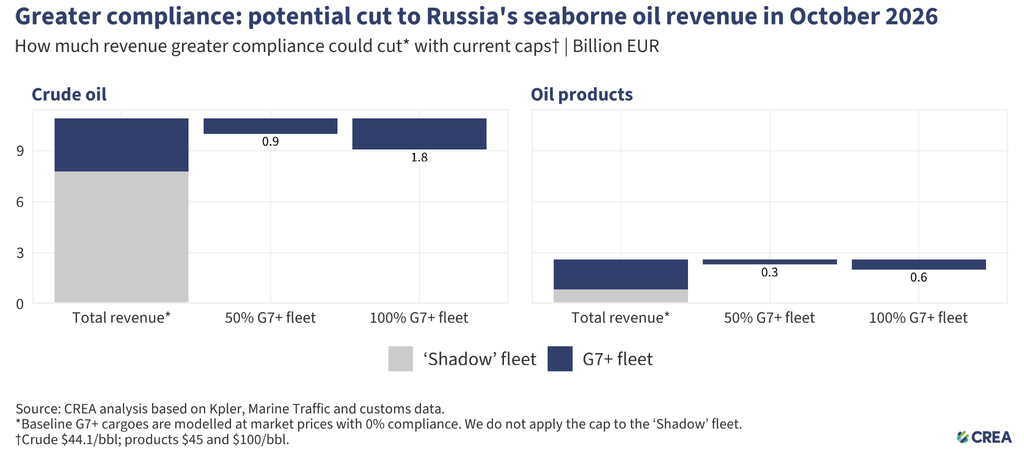
- For the price cap policy to achieve its desired impact, strong enforcement is key. In October 2026, full enforcement of the USD 44.1 per barrel price cap and the two respective oil product price cap levels (USD 100 per barrel for premium to crude oil products and USD 45 per barrel for discount to crude oil products) would have reduced Russia’s total seaborne oil export revenues by 18% (approximately EUR 2.4 bn: EUR 1.8 bn from crude oil and EUR 0.6 bn from oil products) compared to zero compliance with the policy.
- If 50% of Russian oil transported on G7+ tankers had complied with the current price cap levels, Russia’s total seaborne oil export revenues in October 2026 would have been approximately EUR 1.2 bn (9%) lower than under a scenario with no price cap compliance.
Create better enforcement mechanisms for the price cap policy
Sanctioning countries must implement measures that address attestation fraud — a key enabler of non-compliance. Maritime insurers or vessel owners currently do not have direct access to pricing information for the oil they insure or transport and are reliant on attestation documents provided by oil traders for price cap compliance. At the same time, the majority of Russian crude oil is traded by opaque entities located outside price cap coalition countries — such as the UAE and Hong Kong. These traders can fraudulently underreport the price that they paid to attain Western maritime services for the transport of Russian oil.
Maritime insurers and oil traders must be required to obtain bank statements and invoices showing that the Russian oil was traded below the price cap to avoid fraudulent attestation documents being produced. This bank statement must be verified by the bank itself to reduce the risk of the oil trader fraudulently producing documents. It would also enable maritime service providers to independently verify the price paid for the oil.
As an alternative to amending and enforcing the price cap policy, sanctioning jurisdictions could utilise their leverage to tax Russia’s use of G7+ maritime services when transporting its fossil fuels.
Restrict the growth of ‘shadow’ tankers & tighten regulations targeting the refining loophole
- Frequent sanctioning of Russian ‘shadow’ vessels has shifted Russian oil back to tankers owned or insured in G7+ countries. Nonetheless, Russian ‘shadow’ tankers still hold sway over the transport of Russian crude oil. In addition, many sanctioned vessels continue to deliver oil to ports globally, with EU and UK sanctions in particular being frequently violated. Sanctioning countries must align their vessel lists and enforcement paradigms to achieve a greater impact on their operations.
- Maritime coastal states should intensify efforts to monitor, inspect, and detain ‘shadow’ fleet vessels that lack legal passage rights, such as unflagged, unlawfully idle, or security-risk vessels. Authorities must enforce and improve environmental and navigation laws within their territorial waters, investigating and boarding suspicious vessels when justified. Crews involved in criminal activity should face prosecution, and noncompliant ships and personnel should be subject to international arrest warrants.
- In its 18th sanctions package, the EU banned the imports of ‘oil refined from Russian crude’. The regulation bans imports from countries that are ‘net importers’ of crude oil. Net export status does not preclude the import and refining of Russian-origin crude, especially in jurisdictions with flexible or opaque crude sourcing practices. To close this enforcement gap, the exemption should be applied at the refinery level rather than the national level. Refined petroleum products should be subject to import restrictions if produced at facilities that have processed Russian crude within the past six months, regardless of the final product’s declared origin or the host country’s net export position.
- The exemptions for countries including the UK, the US, Canada, Norway, and Switzerland create an opportunity for oil products refined from Russian crude to be re-exported to the EU. This gap should be closed to ensure the sanctions are comprehensive and watertight. The EU should work with its partners to encourage them to also ban the import of oil products from refineries processing Russian crude.
- Imports of oil products or petrochemicals from storage terminals or re-export hubs in non-sanctioning countries that have received a shipment of Russian oil in the previous six months should be prohibited from exporting to sanctioning jurisdictions. This aims to prevent re-export hubs from obfuscating the origin of imported Russian oil products that are then sent to sanctioning countries, as seen in suspicious cases observed in Turkiye and Georgia.
Stronger sanctions enforcement and monitoring of violations
- Despite clear evidence of violations, there is a need for stronger enforcement of penalties by agencies against shippers, insurers, and vessel owners. This information must be shared widely in the public domain. Penalties against violating entities increase the perceived risk of being caught and serve as a deterrent.
- Penalties for violating the price cap must be significantly harsher. If found guilty of violating sanctions, vessels should be fined and permanently banned from accessing Western maritime services or entering ports in sanctioning jurisdictions.
- The G7+ countries should ban STS transfers of Russian oil in their territorial waters. STS transfers undertaken by old ‘shadow’ tankers with questionable maintenance records and insurance pose environmental and financial risks to coastal states and support Russia logistically in exporting high volumes of crude oil. Coastal states should require oil tankers suspected of being ‘shadow’ tankers transporting Russian oil through their territorial waters to provide documentation showing adequate maritime insurance. If they fail to do so and are identified as a ‘shadow’ tanker, they should be added to the Office of Foreign Assets Control (OFAC), UK, and European sanctions lists. This policy could limit Russia’s ability to transport its oil on ‘shadow’ tankers, which are not required to comply with the oil price cap policy.
- To strengthen the integrity of maritime operations, the International Maritime Organization (IMO) must revise its guidelines to enhance transparency regarding maritime insurance. The IMO should mandate that flag states require shipowners and insurers to publicly disclose key financial information, including insurer solvency data, credit ratings from recognised agencies, and audited financial statements. Maritime authorities of coastal states should be legally able and encouraged to detain tankers that fly false flags and therefore pose environmental and security threats. The IMO should also promptly report tankers operating under false flags or with revoked registrations, improving transparency and enabling authorities to better track falsely flagged vessels.
Relevant reports:
- Rubio turns to small Indian town as US faces high oil prices
- Turkey and Morocco Lead Fuel Supplies to Russia as Seaborne Imports Fall 44%
- ‘A dumping ground for blood oil’: Pressure mounts on Canberra over Putin trade ties
- Turkey complains Russian gas too expensive in possible discount bid
See CREA’s live Russian Fossil Fuel Export Tracker and Russia Sanctions Tracker for the latest data on Russian fossil fuel exports and the impact of sanctions.
If you would like to obtain any of the data underlying these charts, please do not hesitate to contact us at queries-russia@energyandcleanair.org.
| Note on methodology: This monthly report uses CREA’s fossil shipment tracker methodology. The data used for this monthly report is a snapshot taken at the end of each month. The data provider revises and verifies data on trades and oil shipments throughout the month. We subsequently update this verified data each month to ensure accuracy. This might mean that figures for the previous month will change in our updated subsequent monthly reports. For consistency, we do not amend the previous month’s report; instead, we treat the latest one as the most accurate data for revenues and volumes. Russia’s daily revenues for commodities used in this report are derived as an average, using CREA’s pricing methodology. The number of vessels with false flags per month is calculated using an end-of-month snapshot. In other words, for each month, vessels were counted if their most recent flag change at the end of the month was to a false flag. This does not account for the vessels with multiple false flag periods (switches between false flags and verified flags, or between different false flags), only the most recent flag status at the end of the month. To calculate the oil delivered by ‘shadow’ tankers under each flag, we count each cargo of Russian crude oil or oil products once, in the month it was unloaded, under the flag flown on the loading date by the tanker that loaded it at a Russian port. A flag is treated as false when the registration in force on the loading date is not recognised by the flag state. ‘Shadow’ tankers are those that were sanctioned on the loading date or were not owned or insured in G7+ countries; G7+ owned or insured tankers that were not sanctioned are excluded. The chart names the three flags, other than the Russian flag, that carried the largest volumes over the 13 months shown. We assume that falsely flagged vessels that have not transported a single cargo in the last 15 months are not operational and therefore exclude them from the analysis. CREA’s estimates of the impact of a revised and lowered price cap have been updated since February 2025. These numbers are a more accurate representation of the revenue losses Russia would incur. |